Keith Go Team
Mortgage Guides & Insights
Practical answers and buyer guidance you can use before you apply or make an offer.
 Mortgage Tips
How to Buy Your Next Home Before Selling Your Current One
You may be able to buy your next home before selling your current one. Compare savings, a HELOC, bridge financing, or an acquisition program based on cash reserves, carrying costs, timing, and risk.
 Mortgage Tips
You Don't Want to Find Out Your Preapproval Was Garbage AFTER You're Under Contract
A mortgage preapproval is only as solid as the income, debts, assets, payment assumptions, and property details behind it. Know what was reviewed before you make an offer.
 Mortgage Tips
Planning to Move to Franklin in 2027? Start the Work Now, Not the House Hunt
Planning a Franklin, Tennessee move in 2027? Start with the full payment, exact property costs, credit, cash, income, and current-home strategy before you start touring houses.
 Mortgage Tips
I've Been Asked About Escrow Accounts 10,000 Times. Here's How They Actually Work
A fixed interest rate does not guarantee a fixed total payment. Property taxes, insurance, and an escrow shortage can change what you owe each month.
 Mortgage Tips
Why the "Maximum Approval" Is the Worst Number to Base Your Home Purchase On
Your maximum mortgage approval is an underwriting limit, not a household budget. Learn the three payment numbers to know before you start looking at homes.
 Mortgage Tips
The Second You Buy a House, You Become a Target. Here Is How to Check What Is Real.
Real property details do not prove a letter, email, text, meeting link, or phone call is legitimate. Here is how to verify a request before you respond.
 Retirement Planning
How Homeownership Can Give You More Choices in Retirement
Home equity can support a move, lower housing costs, home modifications, or future care. Here is how to evaluate those choices and where a reverse mortgage may fit.
 Mortgage Tips
Your Student Loan Payment Came Back. Check It Before You Buy a Home.
A missed federal student-loan payment can show up on your credit and complicate a mortgage. Here is what to check before you start house hunting.
 Mortgage Tips
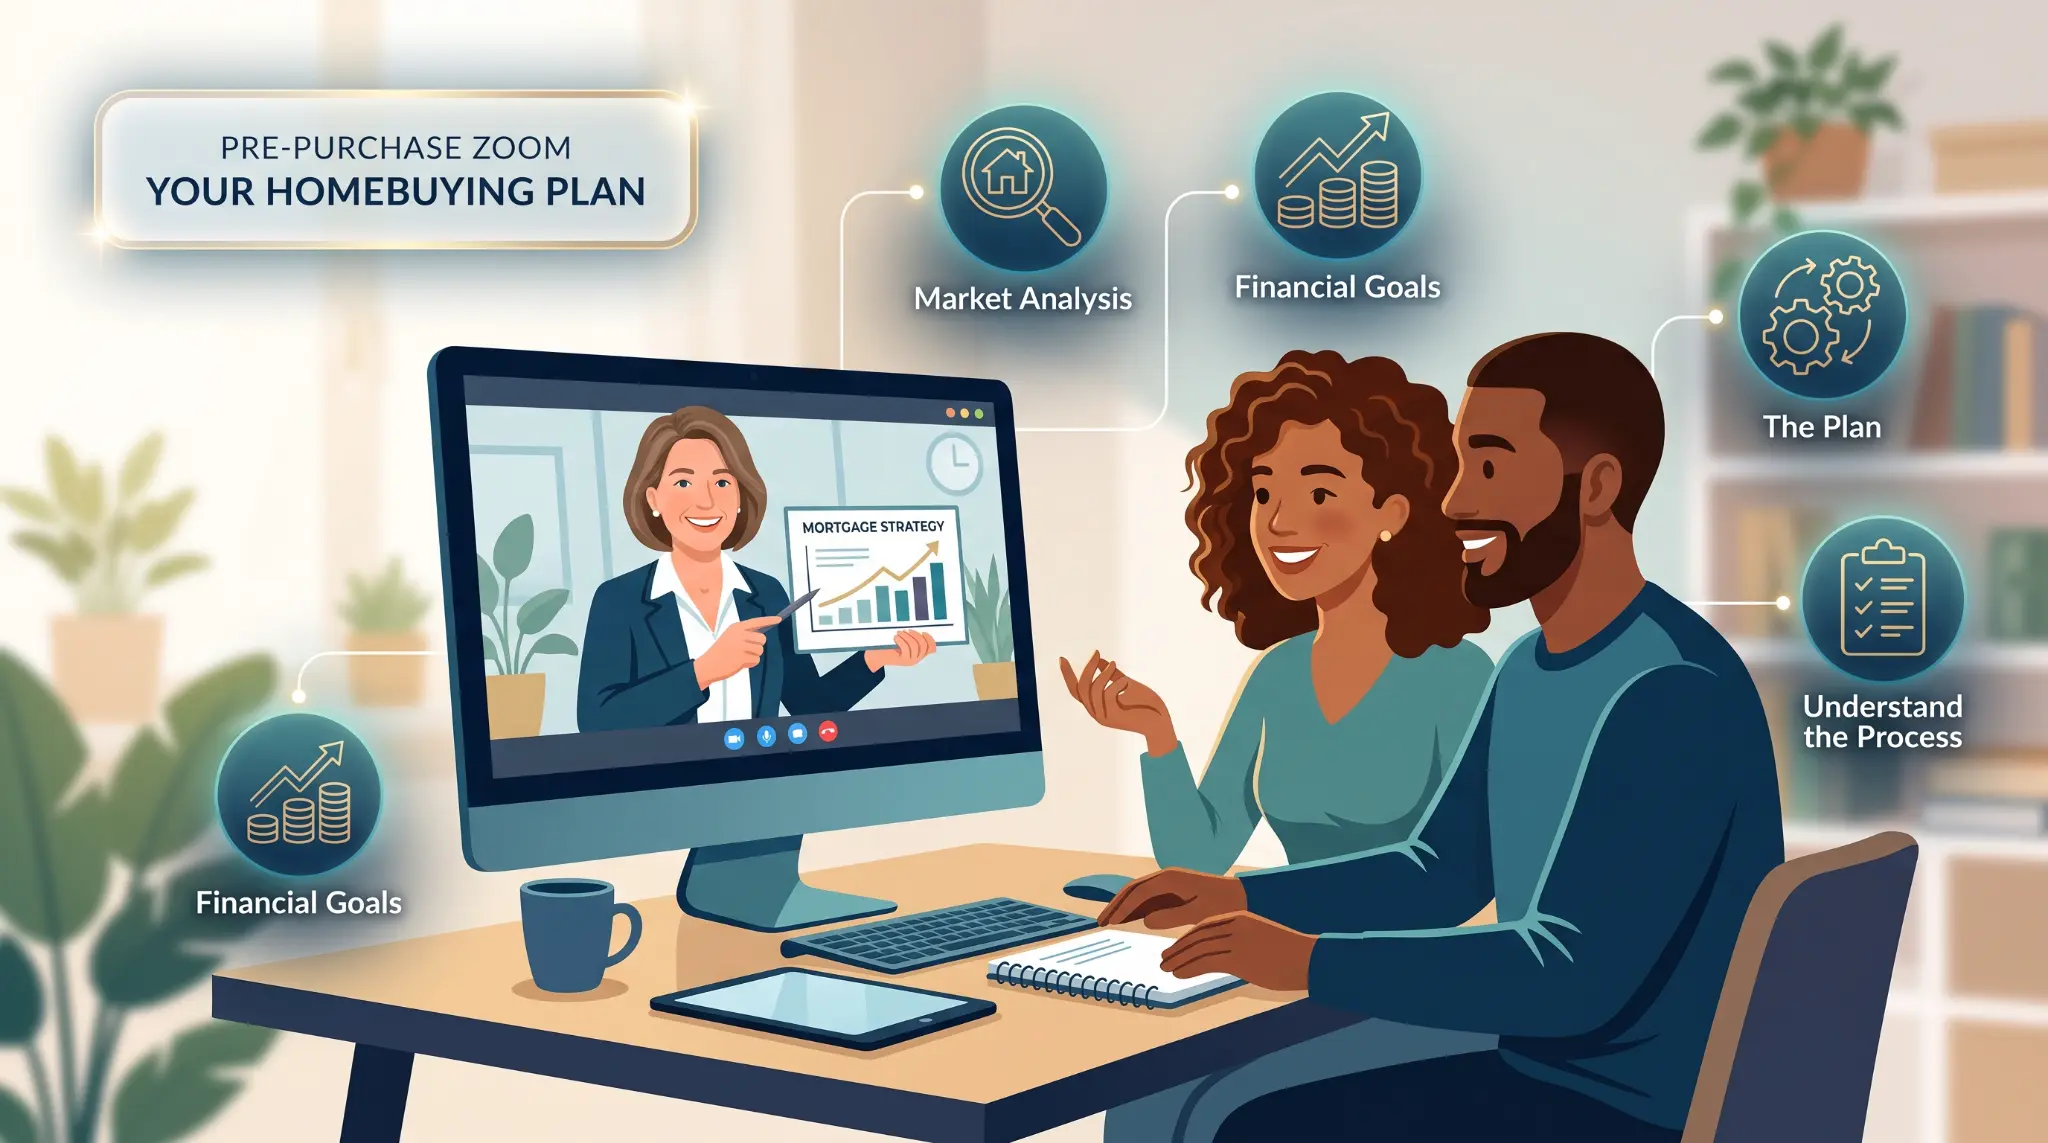
What Happens in a Pre-Purchase Zoom Before You Start Looking for a Home?
A Pre-Purchase Zoom turns a pre-approval into a plan. Here is what we review before you start touring homes, making offers, or comparing loan options.
 Mortgage Tips
Fake Mortgage Mail Is Flooding Mailboxes. Here Is How to Protect Yourself.
An official-looking property letter may be a private solicitation, not a county notice. Here is how to check it before you pay or share personal information.
 Local Area Guide
What It's Like Buying a Home in Franklin, TN: Neighborhoods, Prices, and What to Expect
Franklin, TN sits about 21 miles south of Nashville. This guide covers its housing price ranges, local neighborhoods, school-zone verification, commute questions, and financing choices for buyers deciding where to start.
 Loan Programs
How an $880,000 Franklin Home Became the Right Home With One Renovation Loan
The house wasn't done for them. The location, the lot, the floor plan, and the basement were exactly right. Everything else could be changed. Here is how one renovation loan made it work.
 Credit
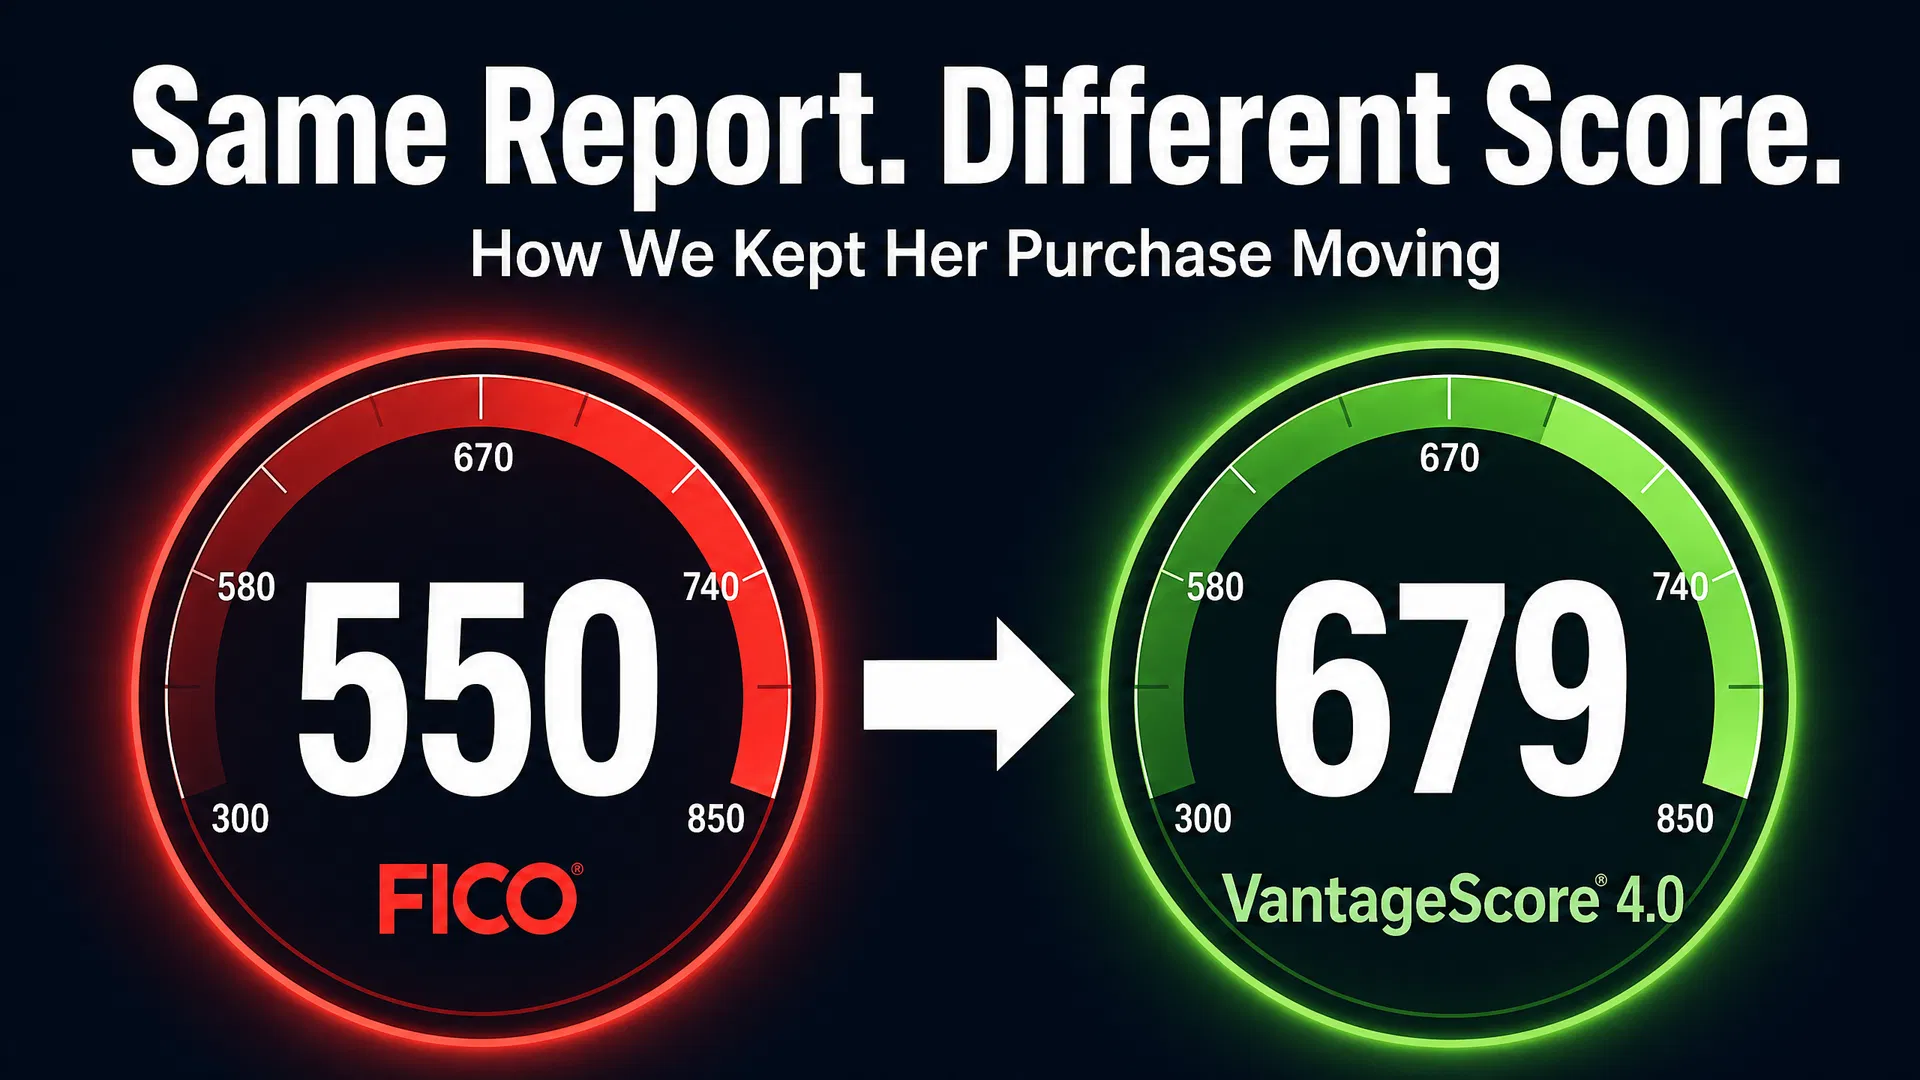
How We Took a Homebuyer From a 550 Credit Score to a 679 in Minutes and Kept Her Purchase Moving
A late payment dropped our client's qualifying mortgage score to 550. Minutes later, we had a qualifying score of 679. We didn't repair her credit. We used a different approved scoring model.
 Home Buying
You're Under Contract. Now What?
Your offer was accepted. Now the real work begins. Here is exactly what happens between contract and closing, step by step, so nothing surprises you.
 Credit
Your Credit Karma Score Went Up. Here Is What That Actually Means for Your Mortgage.
Credit Karma went up 30 points. So did your mortgage score, right? Not necessarily. Here is how to read a free score increase and know when it actually matters for your loan.
 First-Time Homebuyer
You're Pre-Approved. Now What? A Simple Guide to Buying Your Home With Confidence
Getting pre-approved is a big milestone, but it's not the finish line. Here's exactly what happens next and how to protect your approval all the way to closing day.
 New Construction
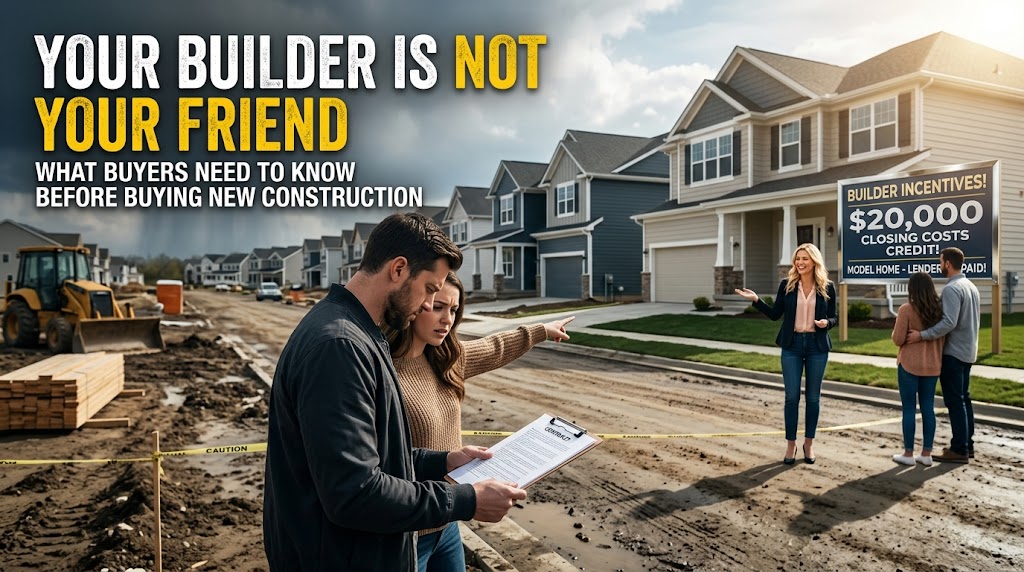
Your Builder Is Not Your Friend: What Buyers Need to Know Before Buying New Construction
New construction feels safe — fresh paint, clean streets, brand-new everything. But in big, still-building neighborhoods there are risks most buyers never see until they are already under contract. Here is what to know before you sign.
 Down Payment Assistance
If You Teach, Fight Fires, Work in Law Enforcement, or Are an EMT, You Can Buy a Home at 50% Off List Price.
The federal government has a program that gives teachers, firefighters, law enforcement officers, and EMTs a 50% discount on the purchase price of certain HUD-owned homes. Most people who qualify have never heard of it.
 Move-Up Buyers
How a Bridge Loan Helps You Buy Before You Sell (Without Moving Twice or Writing a Weak Offer)
You spot the right home but your equity is locked in the house you already own. A bridge loan solves that timing problem. Buy first, sell second, and write a clean offer without a home-sale contingency.
 Down Payment Assistance
You Can Buy a Home With $100 Down. Here Is How the HUD Program Works.
The federal government owns thousands of foreclosed homes and sells them to the public at reduced prices. On eligible properties, you can buy with an FHA loan and just $100 down. Most buyers have never heard of it.
 Credit
Mortgage-Ready Credit™: How to Become Mortgage-Ready in the Next 60 Days
Most people don't need a higher credit score - they need a credit profile optimized for mortgage approval. Here are the 3 biggest credit mistakes future homebuyers make, and what Mortgage-Ready Credit™ actually looks like.
 Down Payment Assistance
There Is Another Down Payment Program in Tennessee. It Goes Up to $35,000.
Most buyers in Tennessee have heard of THDA. Fewer know about The Housing Fund -- a nonprofit that offers up to $35,000 in down payment help, accepts a 600 credit score, and does not require you to be a first-time buyer.
 First-Time Buyers
Tennessee Has Money to Help You Buy a Home. Most People Don't Know It Exists.
THDA — the Tennessee Housing Development Agency — offers down payment assistance up to $15,000 and below-market interest rates to buyers across the state. Here's what it actually covers, who qualifies, and how to use it in Nashville.
 Loan Programs
You Can Buy a Home Right After Bankruptcy. Here's How!
Most people who filed Chapter 7 bankruptcy believe they have to wait years before buying a home. The truth is more hopeful. Here is what is actually possible, what the numbers look like, and what a real path forward looks like for buyers who have been through a hard season.
 Real Story
The $180 That Cost Them Their Dream Home
A couple did everything right - saved for three years, got pre-approved, found the perfect home. Then the payment came in $180 over their number. Here is the tool that would have saved the deal, and how we are covering the cost through June 30.
 Credit & Finance
850 Credit Score? Cute Goal. Here's What Actually Moves the Needle.
You paid off the collections. You got a secured card. You check your score more than your bank account. And somehow you're still in the 600s. Here are the 20 moves that actually raise your credit score - no fluff, no shady hacks, just strategy that works.
 Real Estate Industry
What It Really Takes to Succeed in Real Estate Today: Lessons from Josh Tessier
Josh Tessier of the Lee Tessier Team shares what it actually takes to build a successful, sustainable real estate business in today's market. From the 2008 crash to closing hundreds of homes per year.
 Home Buying Tips
Smart Home Upgrades That Add Value and the Ones That Reduce It
Not all home improvements increase value. Some actually make your home harder to sell. Here is what works, what does not, and what buyers really want in 2026.
 Mortgage Products
50-Year Mortgage Pros and Cons: Who Should Use It and Who Should Avoid It
The 50-year mortgage is all over the news. Everyone has an opinion. Most have never seen one up close. I have. I originated several back in 2004-2005. Let me show you both sides.
 Mortgage Products
The Loan That Died Two Days Before Closing: What Every Homebuyer Should Know About THDA Loans
A THDA loan fell apart two days before closing when a collection dropped the buyer's credit score from 640 to 621. Here is what happened, why it happens, and how to avoid this nightmare.
 Consumer Protection
Do Not Fall for It: The Fake Mortgage Mail Scam Flooding Homeowners
Scammers are sending official-looking mortgage mail designed to trick homeowners into paying thousands for worthless services. Here is how to spot the scam and protect yourself.
 Home Buying Tips
The TRUTH About Home Search Websites (What Lenders Don't Tell You)
Zillow is missing thousands of listings due to a dispute with Compass. Homes.com shows hidden data that can save you thousands in negotiations. Here is how to search smarter in 2026.
About this resource
Straight mortgage answers for Middle Tennessee buyers.
Keith Goeringer, Loan Originator with Barrett Financial Group, NMLS #488023, writes these articles to help buyers ask better questions before they apply or write an offer. Local guides link to official sources when a school zone, city service, tax, or program rule needs current verification.
Who writes the Keith Go Team mortgage blog?
Keith Goeringer, a Loan Originator with Barrett Financial Group, NMLS #488023, writes the practical mortgage guidance and local buyer resources on this site.
What topics does the Keith Go Team mortgage blog cover?
The blog covers buying a home, credit, pre-approval, mortgage programs, down payment options, and local Middle Tennessee buyer questions.
Does the blog cover Franklin and Williamson County home buying?
Yes. Local guides explain the questions buyers ask about Franklin, Williamson County, and the broader Middle Tennessee market. Readers should verify address-level school, zoning, tax, and property details with the relevant official source.
Ready to Take the Next Step?
Get Your Free Mortgage Plan
Keith Goeringer helps Middle Tennessee buyers understand their options before they apply or write an offer.