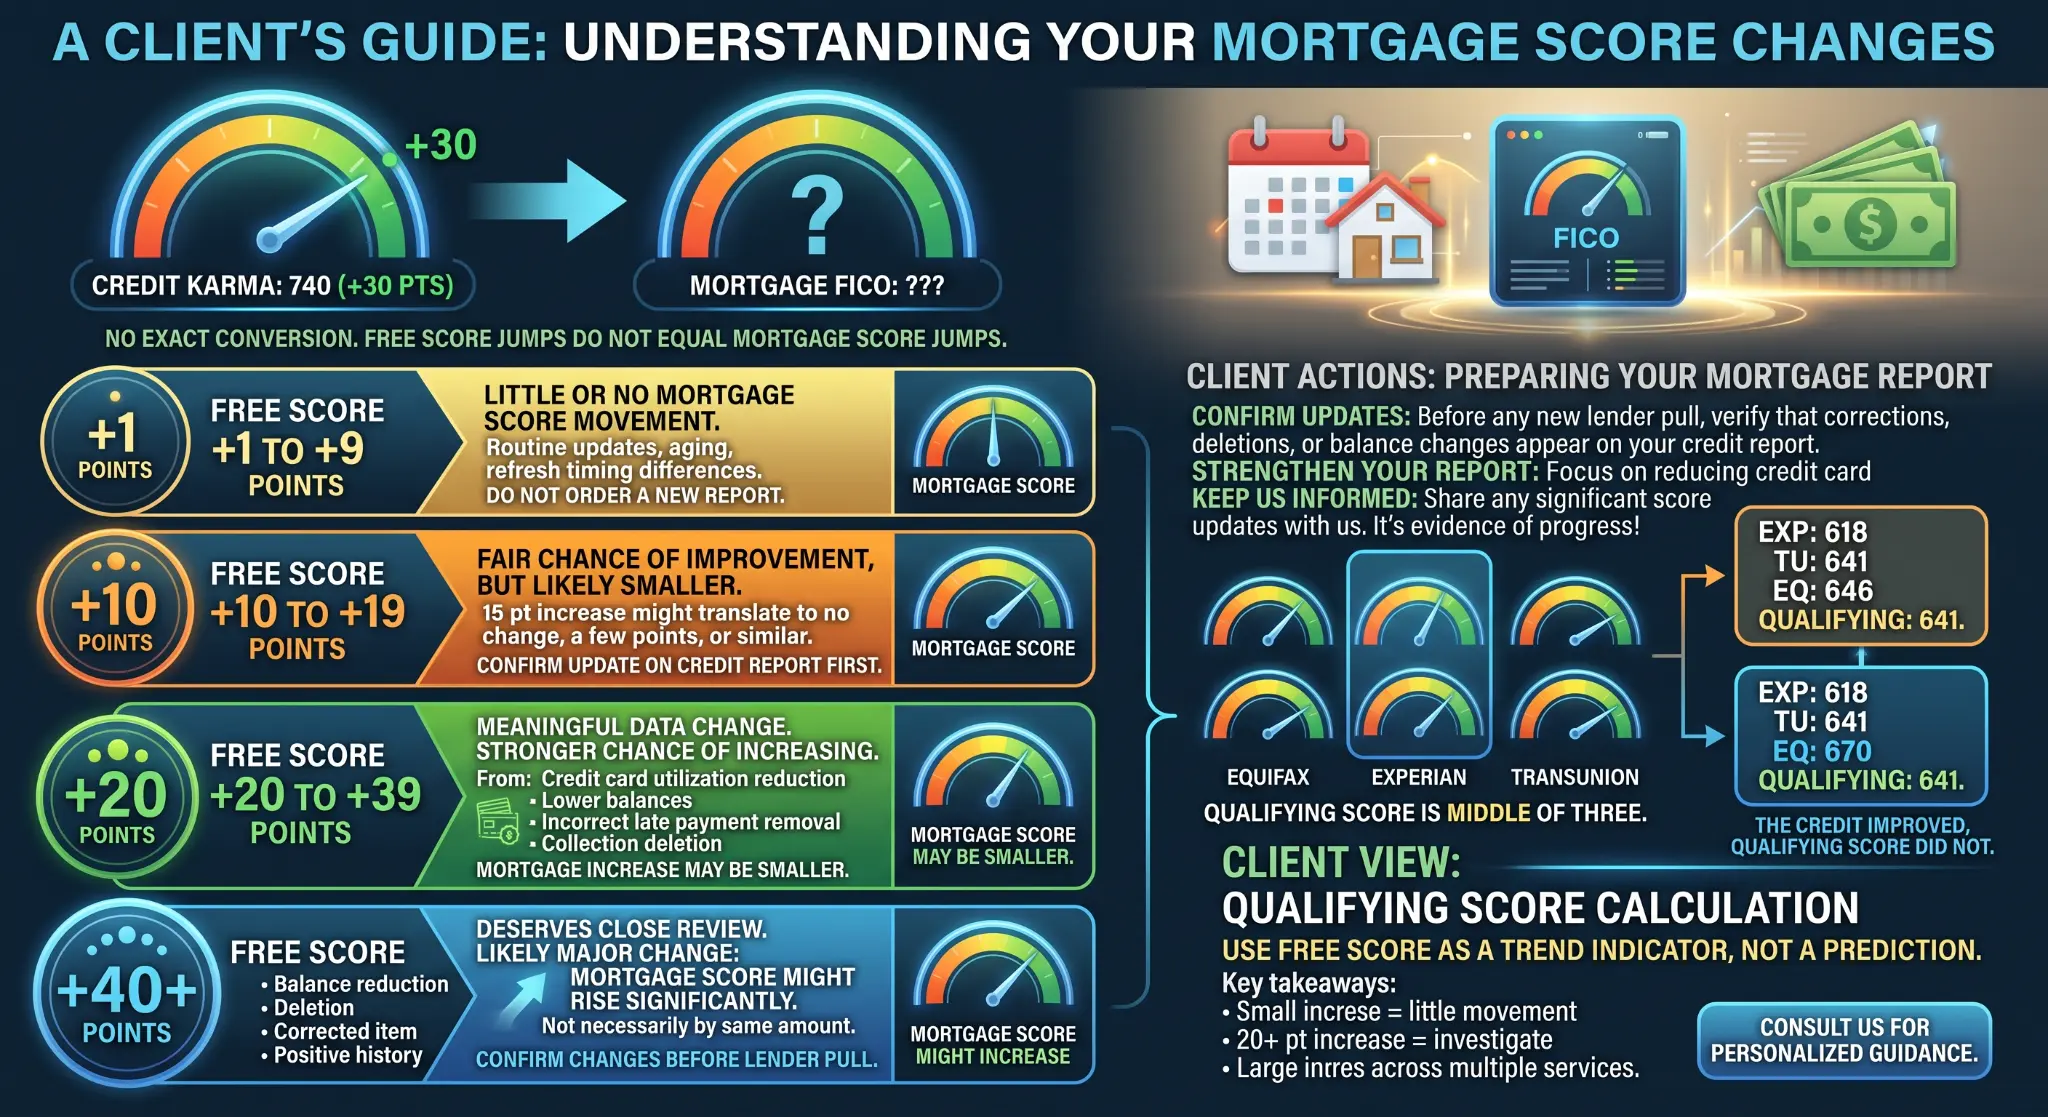
Credit Karma went up 30 points.
So your mortgage score went up 30 points too, right?
Not necessarily.
This is one of the most common questions I get from buyers who are working on their credit. They see a jump on a free monitoring app and want to know if it means their loan is back on track. Sometimes it does. Sometimes it means almost nothing for their mortgage qualification.
Here is how to read a free score increase and know when it actually matters.
The Two Scores Are Not the Same Thing
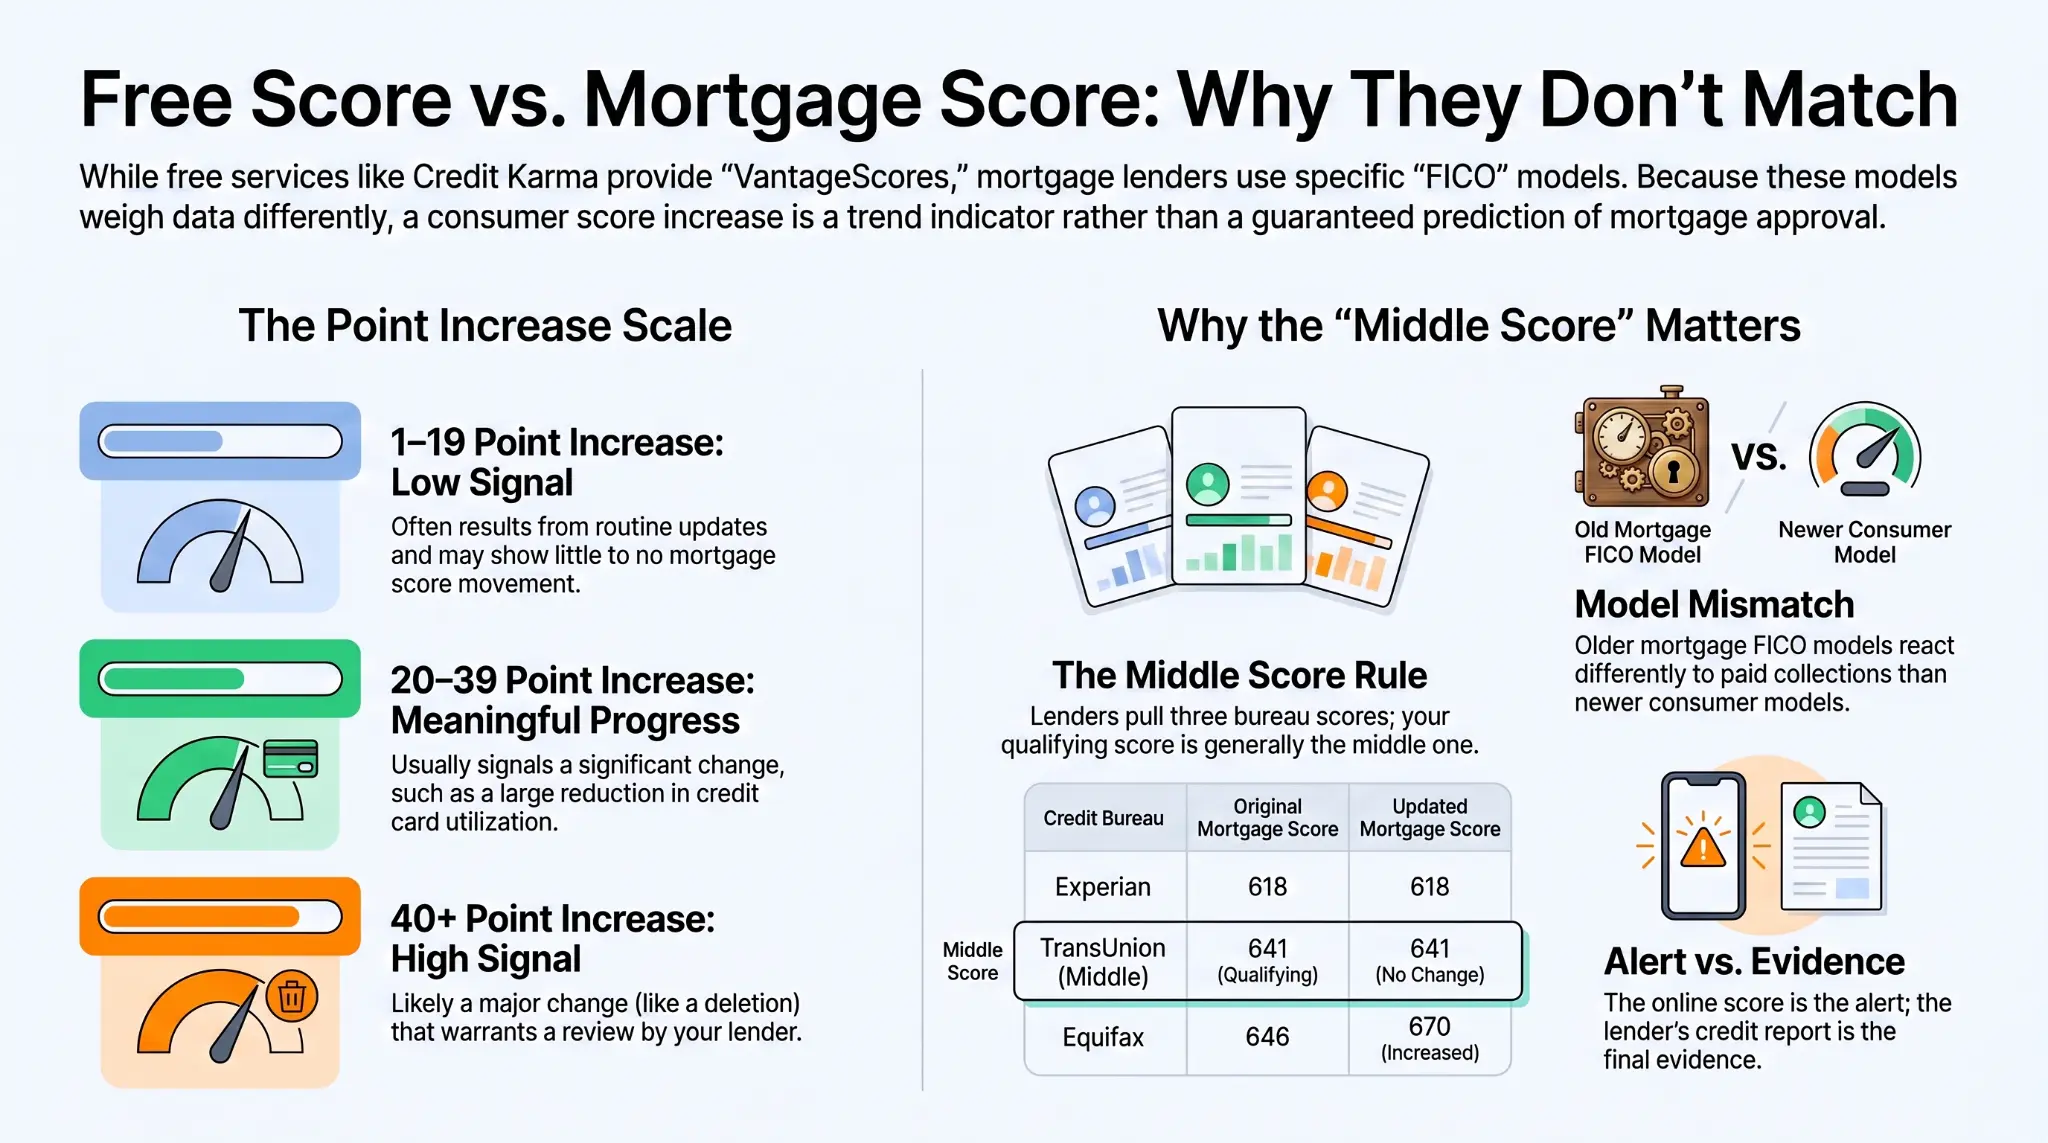
Credit Karma shows a VantageScore. Mortgage lenders use FICO scoring models. Those two models use the same underlying credit report data, but they calculate scores differently.
Mortgage lending also uses older versions of FICO that weigh certain factors differently from the newer models used by free consumer apps. A paid collection might be treated one way by VantageScore and a different way by the FICO version your lender uses.
FICO has said directly that scores produced by other models can differ substantially from a FICO score.
So when your free score moves, the direction is usually the same. The size of the movement often is not.
How to Read a Free Score Increase
Here is a practical guide based on how much your free score went up.
Free score up 1 to 9 points
Your mortgage score probably showed little or no movement.
Small changes like this usually come from routine balance updates, account aging, or differences in when each service refreshed its data. Do not ask your loan officer to pull a new mortgage credit report based on a five-point increase. It is not worth the hard inquiry.
Free score up 10 to 19 points
Your mortgage score has a fair chance of improving, but the increase will probably be smaller.
A 15-point increase on a free service might translate to no change, a few points, or a similar increase on your mortgage score. Before requesting a new lender pull, confirm the balance, deletion, or correction actually appears on the credit report.
Free score up 20 to 39 points
This usually means something real changed in your credit data.
Your mortgage score has a stronger chance of improving when the change came from a large reduction in credit card utilization, several cards reporting lower balances, removal of an incorrect late payment, deletion of a collection, or correction of inaccurate account information.
The mortgage increase might still be smaller than what Credit Karma showed. Treat a 20-to-39-point free score increase as evidence of progress, not proof of a specific mortgage score.
Free score up 40 points or more
A jump this large deserves a closer review.
Something meaningful likely changed: a major balance reduction, an account deletion, a corrected derogatory item, or the addition of positive credit history. Your mortgage score might also rise significantly. It might not rise by the same amount.
Confirm what changed before requesting another lender pull.
Why the Mortgage Score Might Move Less
Older mortgage FICO models sometimes react differently from newer FICO and VantageScore models.
One model might reward a paid collection. Another model might still count the collection's history. One model might respond strongly to a lower card balance. Another gives a smaller increase for the same change.
The bureau also matters.
A TransUnion score increase does not guarantee your Experian or Equifax scores went up. Your mortgage lender reviews all three bureaus. Your qualifying score is the middle of your three scores.
Here is an example.
Say your mortgage scores are:
- Experian: 618
- TransUnion: 641
- Equifax: 646
Your qualifying score is 641.
Now suppose Credit Karma shows a large increase based on Equifax, and the Equifax mortgage score goes from 646 to 670.
Your qualifying score is still 641. TransUnion is still the middle score. The credit improved, but the qualifying mortgage score did not change.
Now suppose TransUnion goes from 641 to 660 instead.
Your new scores are:
- Experian: 618
- TransUnion: 660
- Equifax: 670
Your qualifying score is now 660. That is a real improvement.
This is why the bureau showing the increase matters as much as the number of points gained.
The Strongest Signal
The strongest signal that your mortgage score actually improved is when all three of these things happen at the same time:
The corrected balance or account appears on the credit report.
More than one monitoring service shows improvement.
The service tied to your current middle bureau shows improvement.
If your middle mortgage score currently comes from TransUnion, a TransUnion score increase on Credit Karma or WalletHub matters more to your immediate mortgage qualification than an Experian increase that leaves Experian as your lowest score.
What to Send Your Loan Officer
When you see a meaningful score increase, send a screenshot that shows:
- The name of the credit bureau
- Your previous score
- Your new score
- The date of the change
- The account or balance that changed
- The new reported balance
That gives your loan officer what they need to compare the update with your prior mortgage report and decide whether another pull or a rapid rescore is worth pursuing.
The Simple Rule
Use the free score as a trend indicator. Do not treat it as a prediction.
Under 10 points: wait and keep monitoring.
10 to 19 points: confirm the account update first.
20 to 39 points: meaningful progress worth reviewing with your loan officer.
40 points or more: investigate the change and discuss an updated mortgage report.
The score shown online is the alert. The updated credit report is the evidence. The lender's mortgage credit report gives the final answer.
If you are working on your credit and want to know what your mortgage scores actually look like right now, call me at (615) 955-0461 or start a soft-check application at applywithkeithgo.com. I will review the report with the rest of the file.
Want to see a real example of how scoring models differ? Read: How We Took a Homebuyer From a 550 Credit Score to a 679 in Minutes and Kept Her Purchase Moving.