Catch Saturday Night Live this weekend?
John Mulaney played a hippie at Woodstock in 1969. He's lounging around with the other hippies, chatting about the future, when inspiration hits.
His generation, the baby boomers, should grow up and buy all the houses.
And since they're at it, they might as well take all the money, too.
I laughed. Then I realized the joke has a lot of truth in it.
So I went looking for the real numbers. What I found is worth your time.
The generation sitting on so much of America's housing wealth is also behind a big share of today's home purchases.
Meanwhile, first-time buyers are fighting just to get through the door.
But here's where it gets interesting for Middle Tennessee.
Our market is shifting. Buyers who understand what's going on may have more negotiating power than they've had in years.
Baby Boomers Account for 42% of Home Buyers
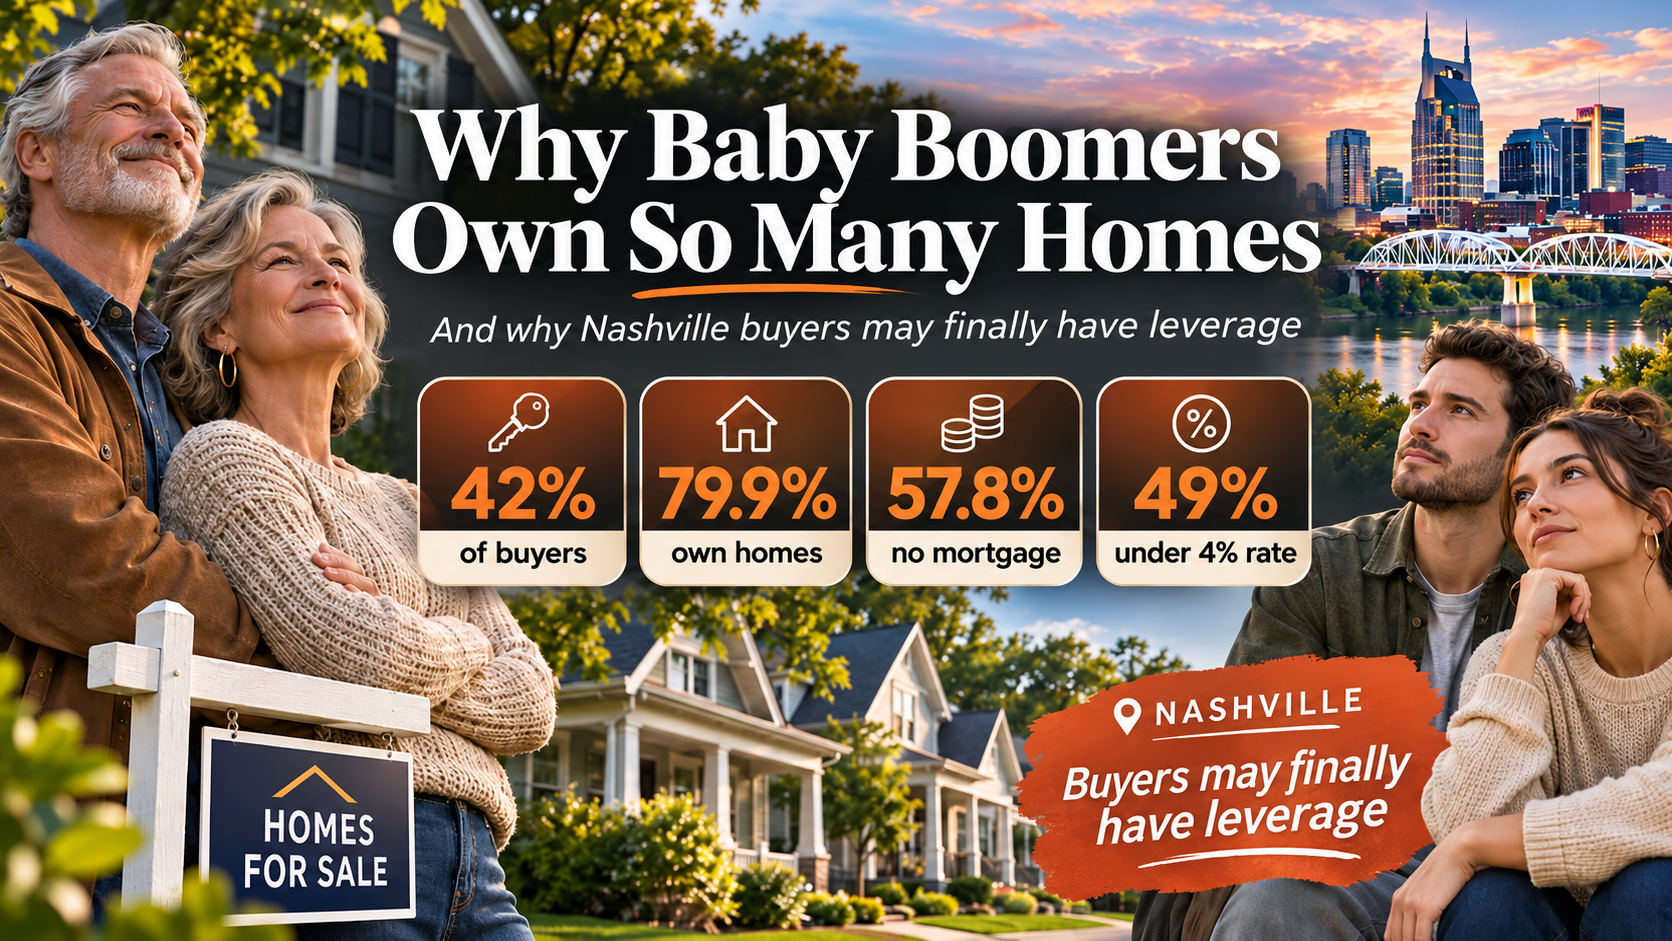
The National Association of REALTORS' April 2026 Home Buyers and Sellers Generational Trends report says baby boomers made up 42% of recent home purchases.
Read that again.
42% of buyers came from a generation born between 1946 and 1964.
Here's the rest of the lineup:
- Millennials: 26%.
- Generation X: 25%.
- Generation Z: 4%.
And first-time buyers? Just 21% of purchases in the April report.
NAR followed up with another study on November 5, 2026. It put first-time buyers at 22%, a small step up from the previous record low.
The typical first-time buyer was 40 years old.
Forty.
Let that sink in.
People are waiting until their late thirties or early forties to buy a first home.
Twenty or thirty years ago, buying in your twenties was a far more realistic goal for many households.
Now people put off homeownership while they save, and they're competing against buyers who already have serious equity.
That distinction matters.
This isn't one generation snapping up houses while another blows its paycheck. The starting lines are in completely different places.
Why Do Baby Boomers Own So Much Real Estate?
I don't think the answer is complicated.
Many boomers made sound financial decisions at a time when housing cost much less relative to income.
They bought homes.
They paid down their mortgages.
They watched values climb.
And plenty of them stayed put for decades.
According to Redfin, 79.9% of baby-boomer households owned their homes in 2025.
Even better, another Redfin study found that 57.8% of baby-boomer homeowners have no mortgage at all.
Paid off. Done.
Now picture someone who bought 30 years ago.
The mortgage may be gone.
The equity is substantial.
Monthly housing costs come down mostly to taxes, insurance, maintenance, and maybe association dues.
So why leave?
Especially if leaving means signing up for a new mortgage payment.
And that brings me to the next problem.
The Mortgage Rate Lock-In Problem
Someone who refinanced in 2020 or 2021 might be sitting on a rate around 3%.
Rates like that rewrote the math.
Realtor.com's October 2026 analysis of Federal Housing Finance Agency data found that approximately 49% of outstanding mortgages carried rates below 4% during the second quarter of 2026.
Now picture a homeowner who bought a few years ago for $350,000.
They've built equity.
They have a low rate.
They may even want something smaller.
But the replacement home is expensive, and the new mortgage comes with a much higher rate.
The new payment could end up higher, even for a smaller house.
So they stay.
Honestly, I don't blame them.
I've spent roughly 25 years in the mortgage business, and one thing has held true: people don't choose housing based on interest rates alone.
They choose based on what owning the home does to their monthly finances.
For someone with a paid-off house or a rock-bottom rate, staying put is often the cheapest move.
That's rational.
But multiply that choice across millions of homeowners and you get a housing inventory problem.
There's Another Side to the Boomer Story
Here's what the SNL sketch skipped.
Boomers aren't only sitting on all the houses.
According to NAR's 2026 generational report, they also made up 55% of home sellers.
More than half.
Some are relocating.
Some want a smaller place.
Some want to be closer to kids or grandkids.
Others want less upkeep, or a home that suits retirement better.
But there's a catch.
Selling a big house doesn't magically produce an affordable starter home.
A boomer might sell a four-bedroom and buy something smaller in the same community.
And with all that accumulated equity, they might buy the new place with a large down payment or even cash.
Now put a first-time buyer in the same race.
One buyer has decades of equity behind them.
The other is trying to save a down payment while paying rent.
That's a tough matchup.
There's more.
Redfin's April 2026 research found that empty-nest baby boomers own 28% of the nation's homes with at least three bedrooms. Millennial families with children own 16%.
I'm not saying older homeowners should be pushed out. It's their property.
But it shows that the housing we already have doesn't always fit the people who need it today.
And a shortage of suitable, affordable downsizing options only makes things worse.
So Why Aren't Younger Buyers Purchasing More Homes?
I think several things are piling up at once.
First, home prices have climbed substantially over time.
Second, mortgage rates are far higher than they were during the pandemic.
Third, saving a down payment is hard when rent, car payments, insurance, childcare, and everything else are eating your paycheck.
Fourth, many buyers don't know what financing options exist.
That last one is where I want to spend my time.
I can't change home prices.
I can't push interest rates down.
And I definitely can't talk millions of boomers into selling.
What I can influence is how a buyer's financing is structured.
Sometimes the gap between buying a home and renting another year comes down to knowing which options are on the table.
That doesn't mean everyone should buy tomorrow.
It means you should run the numbers before deciding homeownership is out of reach.
Nashville's Housing Market Is Sending a Different Message
Let's bring this home.
Greater Nashville REALTORS released its October 2026 housing numbers, and they deserve a look.
Across the nine-county Greater Nashville region:
- Pending sales fell approximately 21% compared with October 2025.
- Closed transactions declined 12%.
- Available inventory increased 8%.
- There were 15,379 active listings.
- Available inventory reached 6.83 months of supply.
- Single-family homes averaged 61 days on the market.
- The median single-family sales price was $499,990, down approximately 3% from $515,000 a year earlier.
That $499,990 figure covers the nine-county region, not Nashville city alone.
Here's what jumps out at me.
Pending sales dropped sharply.
Inventory rose.
But the median price slipped only about 3%.
To me, that says buyers are pickier now, and sellers face more competition for the buyers who are still out there.
It does not say prices are about to collapse.
And it sure doesn't mean every seller will take a lowball offer.
Franklin and Brentwood are not Columbia.
Spring Hill is not Murfreesboro.
And a well-priced home in a sought-after Nashville neighborhood is a different animal from one that's sat for 100 days.
Still, the regional data tells us something useful.
Buyers have more choices, and some sellers have a stronger reason to negotiate.
The opportunity may be in the terms of the deal rather than the price alone.
I'd Rather Negotiate the Right Deal Than Chase the Lowest Price
I wish more homebuyers understood this.
Everyone loves a price cut.
Say you find a home listed at $450,000.
The seller agrees to knock off $10,000.
Nice. You saved $10,000 on the price.
But what does that do to your actual monthly payment?
Depending on the loan structure, the difference may be smaller than you'd expect.
Now try a different angle.
What if the seller put $10,000 toward eligible closing costs or financing expenses instead?
That could reduce the cash you need at closing.
Or it could pay for discount points to get a lower permanent interest rate.
Or, on an eligible loan, it could fund a temporary interest rate buydown.
Each of those leads somewhere different.
A price reduction builds a little more purchase equity and lowers the amount financed, if the down payment structure stays comparable.
A closing-cost credit keeps more of your cash in your pocket.
A permanent rate buydown might lower your payment for the life of the loan, though you'll want to figure out how long it takes to earn back the upfront cost.
A temporary buydown eases the first few years of payments, but the payment eventually returns to the full note-rate amount.
And you still need to qualify under the applicable program requirements.
None of these is automatically the best option.
That's why I like running them side by side.
You don't have to guess which deal wins. We look at the actual financing costs, monthly payments, cash to close, and how long you expect to own the property.
Then you decide with real numbers in front of you.
The Mortgage Payment You Qualify For Isn't Necessarily Your Budget
This is one of the biggest lessons the mortgage business has taught me.
A lender might approve you for a $3,500 monthly housing payment.
But what if you're only comfortable with $2,700?
Which number matters more?
I'd say the $2,700.
You still need to fund retirement.
You still need savings.
You still want a vacation now and then.
And you don't want every surprise expense to turn into a financial emergency.
So when I work with a buyer, I start with the payment they're comfortable making. Then we work backward.
We look at real property taxes.
Realistic homeowners insurance estimates.
HOA dues, when they apply.
Mortgage insurance, when it's required.
And the loan programs that are available.
I also like to walk through the numbers with buyers on Zoom instead of emailing a preapproval letter and waving goodbye as they go shopping.
I want you to understand the payment and your financing options before you sign a purchase contract.
Getting approved and feeling comfortable are two different things.
First-Time Buyers Have More Options Than They Realize
Here's something I see all the time: buyers rule themselves out before they ever talk to anyone.
They assume they need 20% down.
They assume their credit isn't good enough.
They assume student loans shut the door.
Or they assume the payment will be out of reach.
Sometimes those worries are valid. Other times, there are options worth a look.
For example:
FHA financing generally permits down payments as low as 3.5% for qualified borrowers.
Some conventional loan programs allow eligible buyers to purchase with as little as 3% down.
VA financing lets eligible veterans and service members buy with no down payment, subject to applicable program requirements.
USDA financing offers zero-down-payment options for eligible borrowers buying in qualifying areas.
Tennessee also has down payment assistance programs worth reviewing.
The Tennessee Housing Development Agency offers assistance through Great Choice Plus for qualified homebuyers.
Current options include certain deferred second loans and amortizing second loans. Assistance amounts and repayment terms vary, and some options offer additional assistance for eligible new construction.
That doesn't mean everyone qualifies.
Income limits, credit, purchase price, property eligibility, and other requirements all matter.
But I'd rather review your situation and find out what's possible than watch you give up before the numbers get run.
Where I'd Be Looking in Middle Tennessee
If I were starting a home search today, I wouldn't box myself into one subdivision or even one city.
I'd look at the full housing expense and the type of property on offer.
A buyer eyeing Franklin or Brentwood, for example, might find a different price range by widening the search to Spring Hill, Columbia, or parts of Rutherford County.
But that call takes more than a glance at the purchase price.
You have to think about the commute.
Property taxes.
Insurance.
HOA fees.
Possible maintenance.
And how long you plan to stay.
I'd also compare existing homes with new construction.
Builders sometimes offer financing incentives, closing-cost assistance, or rate buydowns.
But I'd want to see the whole financial picture, including the builder's preferred lender offer, instead of assuming a flashy incentive means the lowest overall cost.
I'd also take a hard look at homes that have been sitting longer.
A seller who's been listed for 90 days may have different priorities than someone who listed yesterday.
That doesn't guarantee a discount.
But it gives you a reason to start a conversation.
And the longer a property sits, the more you want to know why.
Is the price too high?
Is there a condition issue?
Did another contract fall through?
Does the seller need time to move?
Those answers should shape your offer.
And don't skip the home inspection just because the seller is willing to negotiate.
Saving money on the purchase doesn't help much if you've bought a problem you never investigated.
What Happens If Mortgage Rates Start Falling?
There's another possibility worth talking about.
Remember all those homeowners with rates below 4%?
Some of them are waiting for a reason to move.
If rates fall enough to improve affordability, more of them might decide to sell. That would add inventory.
But lower rates could also pull more buyers back into the market.
Which happens faster?
Nobody knows for certain.
More inventory might give buyers more choices.
More buyer competition might push prices up.
Both can happen at the same time.
That's one reason I don't like building a homebuying decision around predictions about future rates.
Look at today's price, today's financing terms, and the payment you can afford today.
If rates improve later, refinancing might become an option, subject to costs and qualification.
But a future refinance isn't guaranteed.
Don't build your whole plan around one.
What Should First-Time Buyers Do Right Now?
Here's how I'd approach this market.
First, figure out your comfortable monthly payment.
Not the biggest payment a lender will approve. Your comfortable payment.
Second, complete a real mortgage preapproval.
That means reviewing your credit, income, assets, debts, and documentation. When it makes sense, take the extra steps to strengthen the preapproval before you start writing offers.
Third, compare financing programs.
The loan with the smallest down payment isn't necessarily the loan with the lowest overall cost.
Fourth, work with a Realtor who knows your local market.
You want someone who can tell you which homes are moving, which are sitting, and where sellers have room to negotiate.
Fifth, compare offer structures before you write the offer.
Ask your lender to calculate the difference between a lower price, seller help with closing costs, a permanent rate buydown, and a temporary buydown.
And finally, don't rush.
More inventory and fewer competing buyers means some buyers have extra time to make an informed decision.
Use it.
What About Homeowners Thinking of Downsizing?
There's another side to this conversation.
If you're a homeowner in your sixties or seventies, you shouldn't move just because someone says your generation owns too many houses.
That's ridiculous.
But there are legitimate reasons to look at your options.
Maybe you want less maintenance.
Maybe you want to be closer to family.
Maybe you want a one-level home.
Or maybe you want to put some of your accumulated equity to work in your retirement planning.
The decision deserves the same financial analysis as any other.
What is your current home worth?
How much equity would you walk away with after selling expenses?
What would the replacement home cost?
Would you need a new mortgage?
How would taxes, insurance, HOA dues, and maintenance change?
And what happens to your long-term cash reserves?
Sometimes downsizing saves real money.
Sometimes a smaller house costs more per month than the one you already own.
Better to find out before you sell.
The Bigger Housing Problem Won't Be Solved Overnight
The SNL sketch was funny because it touched a nerve with a lot of younger buyers.
Baby boomers hold a substantial share of America's housing wealth.
A large percentage of them own their homes outright.
And many have little financial reason to move.
But blaming an entire generation doesn't fix anything.
We need more housing people can afford.
We need better options for people who want to downsize.
And we need buyers to understand their financing options instead of assuming homeownership is impossible.
I can't solve the country's housing shortage.
But after roughly 25 years in the mortgage business, I know how much the right financing strategy can change an individual transaction.
And right now, Middle Tennessee buyers have something they haven't always had.
More choices.
More time to compare homes.
And, in some cases, more room to negotiate.
The real question isn't whether baby boomers bought all the houses.
It's whether there's a house available today that fits your budget, your needs, and your long-term financial plans.
That's a much better place to start.
Let's Look at Your Numbers
If you're thinking about buying in Nashville, Franklin, Brentwood, Spring Hill, Columbia, Murfreesboro, or anywhere in Middle Tennessee, I'd be happy to review your situation.
We'll look at your comfortable monthly payment, available loan programs, expected cash to close, and possible ways to structure an offer.
And if you're a Realtor with a buyer who feels priced out, send me the scenario before assuming the financing won't work.
Sometimes the answer is no.
Sometimes there's an option nobody has looked at yet.
Either way, I want you to have the numbers before you decide.
Visit KeithGo.com or email me at keith@keithgo.com .
Keith Goeringer
Mortgage Loan Officer
Middle Tennessee
Related Reading
When the Mortgage Computer Says No, Is There Another Way?
Research and Sources
- National Association of REALTORS, 2026 Generational Trends, April 15, 2026
- National Association of REALTORS, 2026 Profile of Home Buyers and Sellers, November 5, 2026
- Redfin, 2025 Homeownership by Generation
- Redfin, The Great Housing Mismatch, April 2026
- Realtor.com Economic Research, Outstanding Mortgage Rates, Q2 2026
- Greater Nashville REALTORS, October 2026 Housing Report
- Tennessee Housing Development Agency, Down Payment Assistance