A good friend of mine called me this week - a loan officer I've known for years. She's sharp, organized, and never panics. Except this time, she did. Her client's THDA loan fell apart two days before closing.
What Went Wrong
THDA stands for Tennessee Housing Development Agency. They offer a down payment assistance program for buyers who need help with their down payment. But there's one part that catches people off guard: THDA re-pulls your credit right before closing. That's what killed this deal.
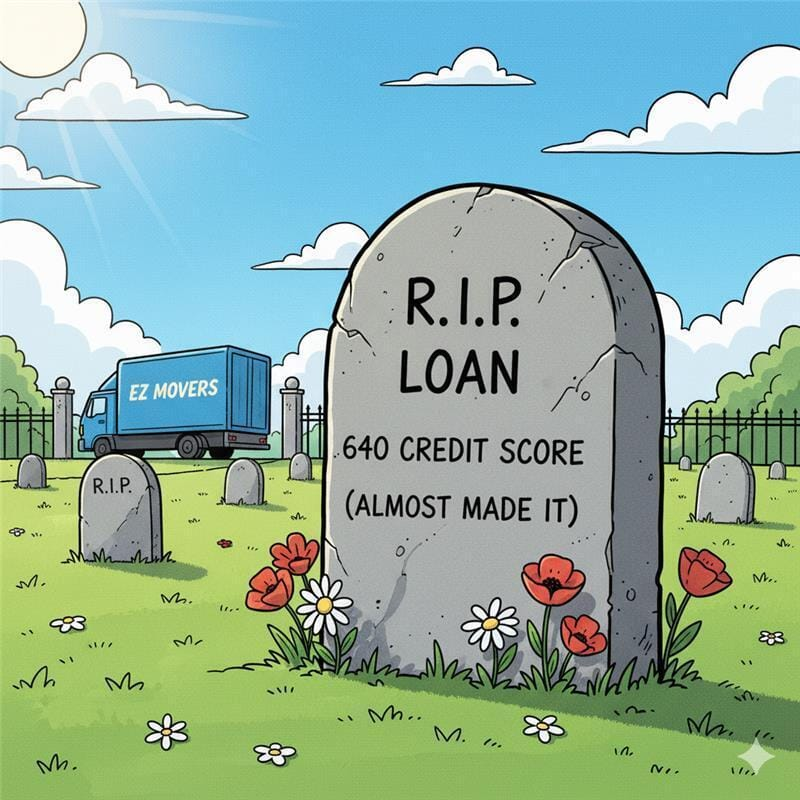
The buyer had a 640 credit score - exactly what THDA requires. The loan was approved, the moving trucks were ready, and everyone was celebrating. Then, a Verizon collection suddenly appeared on his credit report. His score dropped to 621. THDA's minimum is 640. The deal died instantly.
The Human Side
The buyer was a single dad with three kids. He'd done everything right - took the required homebuyer education class, submitted every document, and stayed on top of everything. Two days before closing, he's told: you can't buy the home. The seller's furious. The agent's scrambling. The buyer's crushed.
Why This Happens
To be clear, THDA's heart is in the right place. But their system has two big tripwires: they re-pull your credit at the end, and they re-underwrite the entire file right before closing. That means if anything changes - your job, your debts, even a balance increase - the loan can be denied after you've paid for your inspection, appraisal, and moving expenses.
How We Saved It
We switched the buyer into a lender-backed down payment assistance program. These are run directly through the lender - and that changes everything. No income caps, no last-minute re-pulls, one underwriting process, and faster, smoother closings. The rate's a bit higher, but the reliability makes it worth it.
The Takeaway
If your credit score is hovering around 640 or 641, you're walking a tightrope. Build in a cushion, don't max out your qualifications, and if you can, save 3 - 3.5% for your own down payment. Sometimes patience costs less than heartbreak.