I recently worked with a buyer who had an $800,000 home, a good income, and enough money in the bank to make the down payment on his next house.
He qualified for both mortgages.
That wasn't the problem.
The problem came up when we started looking at how much cash he would have left after closing.
He and his wife could put 5% down on the new house, but doing so would use nearly all their available savings. Their current home had substantial equity, and they expected it to sell. They just didn't know exactly when.
He told me, essentially, “Keith, I know this house will sell. I'm just concerned about getting rid of all our reserves before it does.”
I understood that concern.
There's a big difference between qualifying for two mortgages and being comfortable carrying two mortgages. You can have an excellent income, plenty of equity, and a perfectly good loan approval while still feeling uneasy about what happens if your existing house takes three or four months to sell.
So we started looking at alternatives.
Could he use a home equity line of credit? Would a bridge loan make sense? Was there another way to access the equity in his current property without waiting for a traditional sale?
That's the conversation I want more homeowners to have before they assume they must sell their current house first.
Your Home Equity and Your Available Cash Are Two Different Things
Let's say you own a house in Franklin worth $800,000 and owe $250,000 on the mortgage.
On paper, you have approximately $550,000 in equity.
That's a substantial amount of money. But it isn't sitting in your checking account, ready to use for a down payment.
To turn that equity into cash, you generally need to sell the property or arrange some type of financing against it.
Now imagine you've found a smaller home in Spring Hill that you would love to buy. Or perhaps your family needs more space, and you've found the right house in Brentwood.
You can afford the next mortgage. You just don't want to sell your existing home before you know where you're going.
That's a reasonable concern, especially if selling first would mean finding temporary housing, storing furniture, and moving twice.
Fortunately, selling first isn't the only possible approach.
The right answer depends on how much equity you have, how much cash you need, whether you qualify to carry both properties, and how much financial risk you're comfortable taking while your existing home is on the market.
Option One: Buy the Next House With Your Existing Savings
This is where I started with my $800,000 buyer.
He had the money for the down payment. He qualified for the new mortgage even with his existing mortgage payment.
From a lending standpoint, the transaction was possible.
But I don't think a mortgage approval should be the end of the financial conversation.
Suppose you have $60,000 available and need $50,000 for your down payment and closing costs. You could complete the purchase, but you'd have only $10,000 left in readily available savings.
Meanwhile, you still own your original home.
You might have two mortgage payments, two sets of utilities, and maintenance expenses on both properties. If something unexpected happens, your financial cushion is smaller than it was before the purchase.
Some homeowners are comfortable with that arrangement. Others aren't.
Neither response changes what the lender says you qualify for.
That's why I want to know how much money you want left in the bank after closing, not simply whether you have enough to close.
Option Two: Use a HELOC to Access Your Equity
A home equity line of credit, or HELOC, allows you to borrow against the equity in your existing property.
You keep ownership of the home and generally continue making your original mortgage payment. You also make payments on the HELOC according to its terms.
For a homeowner who needs a relatively modest amount of money for the next down payment, this may be worth evaluating.
Let's return to the buyer who needs 5% down.
Instead of using nearly all his savings, he might be able to obtain a HELOC against his current house and use those funds toward the purchase, subject to the applicable mortgage and HELOC requirements.
That could help preserve his cash reserves.
But now we have another question.
What does carrying the HELOC cost while the existing house is waiting to sell?
He could have his original mortgage payment, the HELOC payment, and the mortgage payment on his new home.
The HELOC might still be an economical choice. We just need to calculate the payments and total costs rather than assuming that preserving savings automatically makes it the best solution.
And we need a plan for paying off the HELOC when the original property sells.
Option Three: Consider a Bridge Loan
A bridge loan is another way to access equity in a home you're preparing to sell.
These loans are designed for situations where the timing of two transactions doesn't line up neatly.
Depending on the lender and program, the loan may provide funds toward the next purchase, with repayment expected when the original property sells.
The structure, fees, interest charges, payment requirements, and repayment deadlines vary.
That last point matters.
If you're considering bridge financing, I want to understand what happens if your home doesn't sell on the schedule you originally expected.
A bridge loan may be an appropriate solution, but we need to evaluate it alongside your other options.
A homeowner with substantial equity and a short expected selling timeline may have a very different set of choices from someone whose existing property needs major repairs or has already been listed for several months.
Option Four: An Acquisition Program That Lets You Move Before the Final Sale
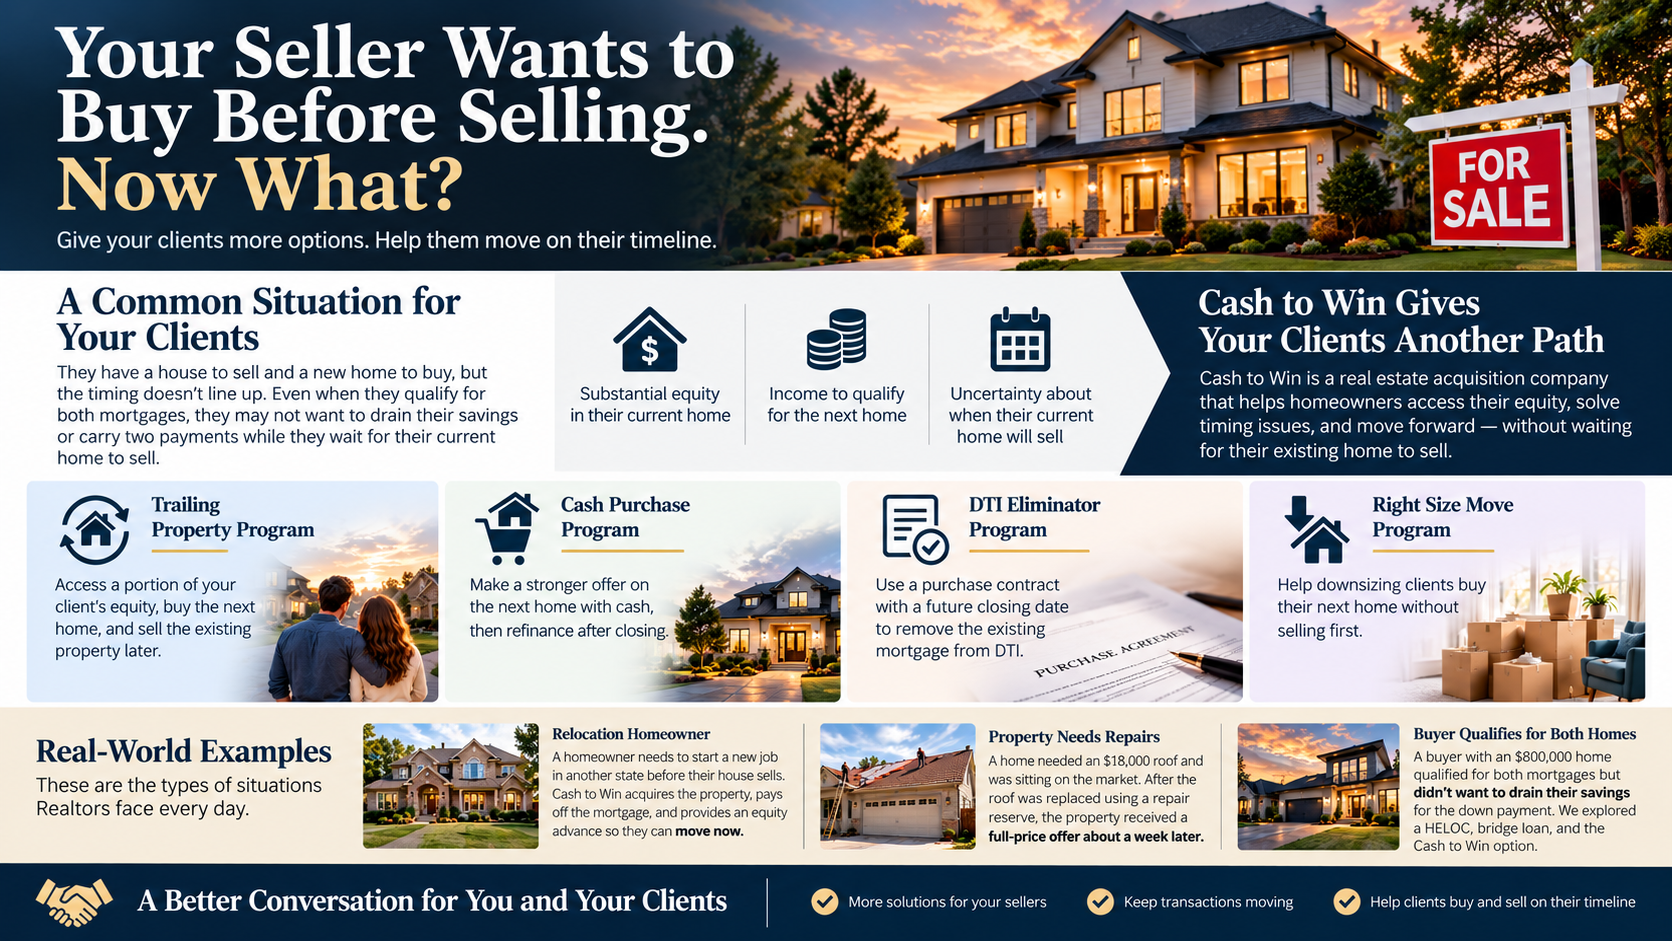
I recently had a conversation with Brian, the founder of a company called Cash to Win.
His company offers a different approach to the buy-before-you-sell problem.
Rather than simply lending money against the existing house, Cash to Win can acquire the property and provide the homeowner with an initial equity payment.
The homeowner can then use the available proceeds toward the next purchase.
The original property is marketed for resale, and the remaining proceeds are distributed according to the agreement after the property sells and the applicable expenses are deducted.
Brian explained that his company typically uses an initial advance of approximately 70% of the property's value, although the actual amount depends on the transaction.
Here's how that might look.
ILLUSTRATIVE EQUITY EXAMPLE
$800,000
Estimated value of your current home
Initial acquisition amount at 70%
$560,000
Existing mortgage payoff
−$250,000
Potential initial funds
Before program fees, closing costs, and adjustments
$310,000
That $310,000 is not the homeowner's total profit, and it isn't a guaranteed amount available at closing. It's a simplified illustration of the initial funds before expenses.
The property still needs to sell to its eventual buyer. The resale price, acquisition fee, carrying charges, real estate commissions, closing costs, and other contractual expenses affect the final amount the homeowner receives.
In our conversation, Brian described an acquisition fee of 1.5% of the acquisition amount, along with a daily carrying charge. The exact daily rate and complete transaction costs would need to be confirmed for a particular property.
The important difference is the transaction structure.
Instead of waiting for the final sale to access equity, the homeowner may be able to receive funds earlier and complete the next purchase.
That can be valuable when timing is the main obstacle. It doesn't automatically make the program less expensive than a HELOC or bridge loan.
We still have to compare the numbers.
What If You Want to Downsize but Don't Want to Move Twice?
This is one of the situations that caught my attention during the conversation with Brian.
Imagine you've lived in a large, two-story home in Franklin for 20 years. The kids have moved out, and you no longer need all that space.
You find a smaller, single-level home that would be perfect.
But you haven't sold your current property.
You could sell first and hope something suitable is available when you're ready to buy. You could move into temporary housing. Or you could try to coordinate two closings within a few days of each other.
None of those options is particularly appealing if your goal is to simplify your life.
Brian described working with homeowners in this situation through a downsizing program he calls Right Size Move.
The idea is to help the homeowner purchase the smaller property while the company handles the acquisition and subsequent resale of the original home.
Depending on the equity available and the price of the next property, the homeowner might need a smaller mortgage or potentially no mortgage at all.
The actual outcome depends on the numbers.
What I like about exploring this type of arrangement is that it addresses the homeowner's entire move, not just the mortgage.
The question becomes whether the convenience and flexibility justify the additional transaction costs.
For someone who has no particular deadline and plenty of available cash, a traditional sale might make more sense.
For someone who has found the right home and absolutely doesn't want to move twice, the comparison may look different.
What If Your Current House Needs Repairs Before It Can Sell?
Here's another problem that can complicate buying before selling.
Your existing house has plenty of equity, but it needs work.
Perhaps the roof is approaching the end of its useful life. Maybe the property needs new flooring, paint, or other repairs before it's ready for the market.
You don't want to spend another $20,000 out of savings, particularly when you're trying to purchase your next home.
During our conversation, Brian described a property in Phoenix that needed an $18,000 roof.
According to his account, the property had been sitting on the market, and the roof was creating problems with prospective buyers.
His company arranged for the replacement. The property was temporarily removed from the market, the roof was completed, and the house was relisted.
Brian reported that the property received a full-price offer approximately one week later.
That's one transaction reported by the company, not a promise that spending money on repairs will produce the same result elsewhere.
But the financing problem is familiar.
A homeowner can have substantial equity without having enough readily available cash to complete necessary repairs.
Brian explained that Cash to Win can sometimes establish a repair reserve from the initial acquisition proceeds.
For example, if the initial acquisition amount were $350,000 and the property needed $20,000 in approved repairs, the company might set aside those funds and coordinate payment to the contractors.
That would reduce the homeowner's initial proceeds, but it could provide a way to prepare the property without requiring the homeowner to pay the contractors directly from savings.
The company would need to approve the property, repair plan, and transaction structure.
And we'd still want to know whether the expected improvement in the property's marketability justified the expense.
An $18,000 roof doesn't automatically create $60,000 in additional value.
Sometimes repairs make financial sense. Sometimes selling the property as-is is the better decision.
The important part is evaluating both options before spending the money.
What Happens If Your House Takes Six Months to Sell?
This is the question I would want answered before committing to any buy-before-you-sell strategy.
It's easy to build a financial plan around the assumption that your house will sell in 30 days.
It's a little harder to build one that still works if the property takes six months to sell.
With a traditional purchase using your savings, you need to determine how long you can comfortably carry both properties.
With a HELOC, you need to account for the additional borrowing costs and payments.
With a bridge loan, you need to understand the repayment deadline and what happens if the original property hasn't sold.
With an acquisition program, you need to understand the carrying charges, the resale agreement, and how a lower-than-expected resale price would affect your remaining proceeds.
You also need to know who controls pricing decisions, what happens if the property needs additional repairs, and what obligations remain after the company acquires it.
These aren't reasons to dismiss any particular approach.
They're the questions that determine whether the approach is appropriate for you.
The Cheapest Option and the Most Convenient Option Might Be Different
This is something I think homeowners need to understand before making a decision.
Suppose you could use a HELOC to access the down payment for your next home.
That might produce a lower total cost than an acquisition program.
But you'd still be responsible for the existing mortgage, the HELOC, and the new mortgage until your original property sells.
Alternatively, an acquisition program might allow you to move forward without continuing to carry those same monthly obligations.
The program would have its own costs, which could be deducted from the proceeds of the eventual resale.
That doesn't mean the costs disappear.
It means the payment structure and timing are different.
For one homeowner, minimizing total transaction costs might be the highest priority.
For another, preserving cash reserves could be more important.
Someone else might be willing to pay additional fees to avoid moving twice or to reduce the uncertainty associated with carrying two homes.
None of those priorities is unreasonable.
But you need to know which problem you're solving.
Otherwise, it's easy to compare two financing options based on a single number while overlooking everything else.
How I Would Evaluate Your Situation
If you came to me and said, “Keith, I found my next house, but I haven't sold the one I'm living in,” I wouldn't immediately recommend a bridge loan or tell you to get a HELOC.
I'd want to understand the entire situation.
First, what is your existing home worth, and how much do you owe?
Next, how much money do you need for the next purchase?
Then we'd look at your available savings, how much cash you want to preserve, and whether you qualify to carry both properties.
We'd also talk about the expected selling timeline.
Is your existing house ready to list tomorrow? Does it need repairs? Are you relocating for a job? Have you already found the next property?
Those details can completely change the recommendation.
From there, we can compare the practical options.
| Approach | What we'd need to evaluate |
|---|---|
| Use existing savings | Cash remaining after closing and the cost of carrying both homes |
| HELOC | Available equity, loan terms, monthly payments, and payoff plan |
| Bridge loan | Fees, repayment deadline, and requirements if the sale is delayed |
| Acquisition program | Initial proceeds, all fees, carrying charges, resale terms, and expected final proceeds |
| Sell first | Selling timeline, temporary housing costs, and the availability of the next home |
I want you to see what each approach does to your finances, not just whether it gets you into the next house.
And sometimes, after reviewing everything, the answer will be to sell traditionally before buying.
Brian made that point during our conversation. He described situations where his company evaluated a homeowner's circumstances and recommended a traditional sale instead.
I appreciated hearing that because an additional financing structure should solve a problem, not create an unnecessary expense.
You Might Be Able to Buy Before You Sell. You Still Need a Plan.
Let's return to my $800,000 buyer.
His income wasn't the obstacle. His mortgage approval wasn't the obstacle.
He had enough money to make the down payment.
What concerned him was using nearly all his savings while waiting for the existing house to sell.
That's a legitimate financial concern, and it deserves more consideration than simply telling him he qualifies.
We're evaluating the available options because I want him and his wife to understand what each one would mean for their cash reserves, monthly obligations, and eventual sale proceeds.
I don't want them making the decision based on an assumption that their house will sell quickly.
And I don't want them paying for an elaborate financing structure if a simpler option accomplishes the same thing.
If you're thinking about moving from Franklin to Spring Hill, downsizing in Brentwood, relocating to Middle Tennessee, or purchasing your next home anywhere else we can serve you, the first step isn't necessarily putting your existing house on the market.
It's figuring out how the two transactions can work together.
You may have more options than you realize.
If you're considering buying before selling, we can review your existing mortgage, available equity, cash reserves, and next purchase. I'll help you compare the financing options and identify the questions that need to be answered before you commit.
You don't need to have the entire move figured out before we talk.
You just need to know where you'd like to go next.