The Fed chair went to Jackson Hole and threatened a rate hike without putting one on the calendar.
That is the kind of speech that makes mortgage rates twitch. Treasury yields moved higher, and the bonds behind mortgage pricing did not get a friendly day.
Not a panic day. Not a gift either.
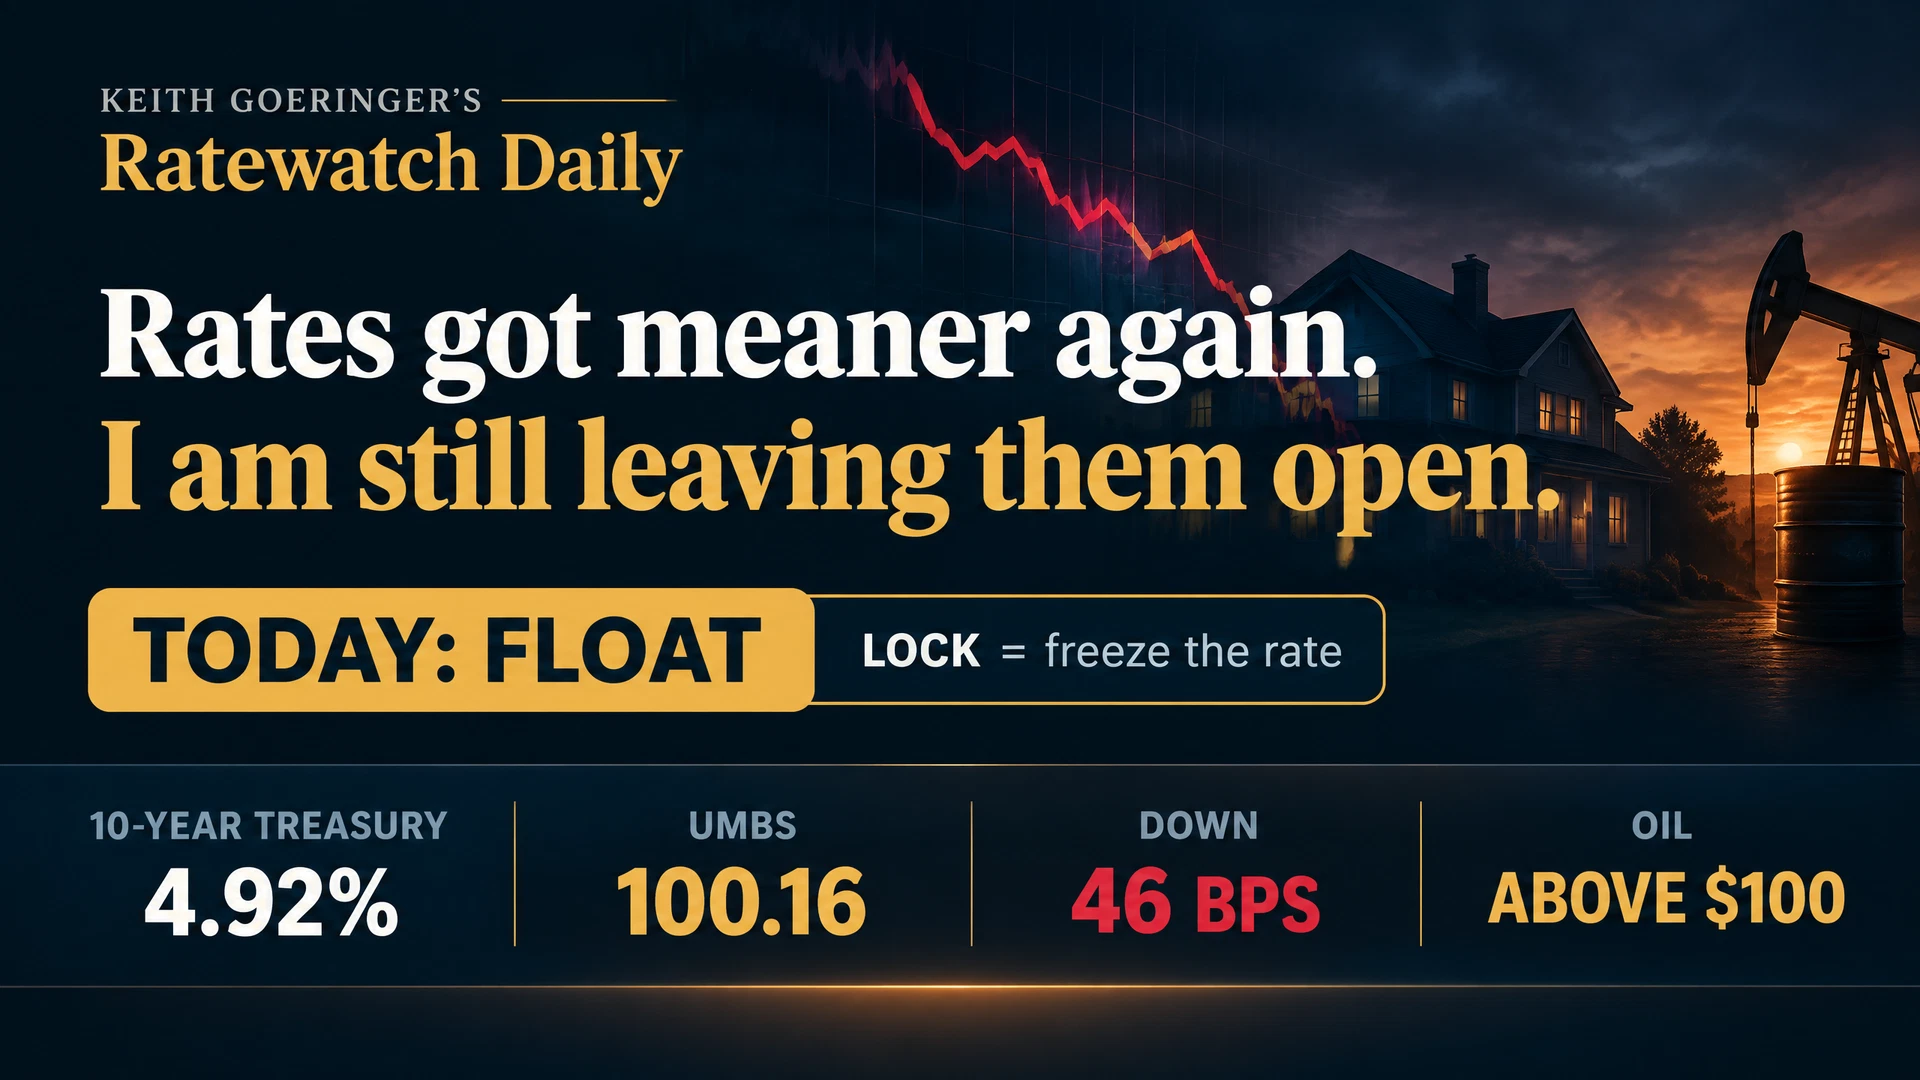
If you already have a loan in process, this is a day to watch your rate options. Waiting is not the same as ignoring it. Floating is not the right choice for every file.
What the Fed actually said
Warsh is more worried about inflation than he has been in a while. The cooler summer numbers did not impress him.
He said the economy does not look squeezed. Unemployment was 4.1%, which he described as consistent with full employment.
The money line was simple. If the Fed is not confident inflation is heading to its 2% goal, officials still have “work to do.”
In English, another hike is possible. He just did not put one on the calendar.
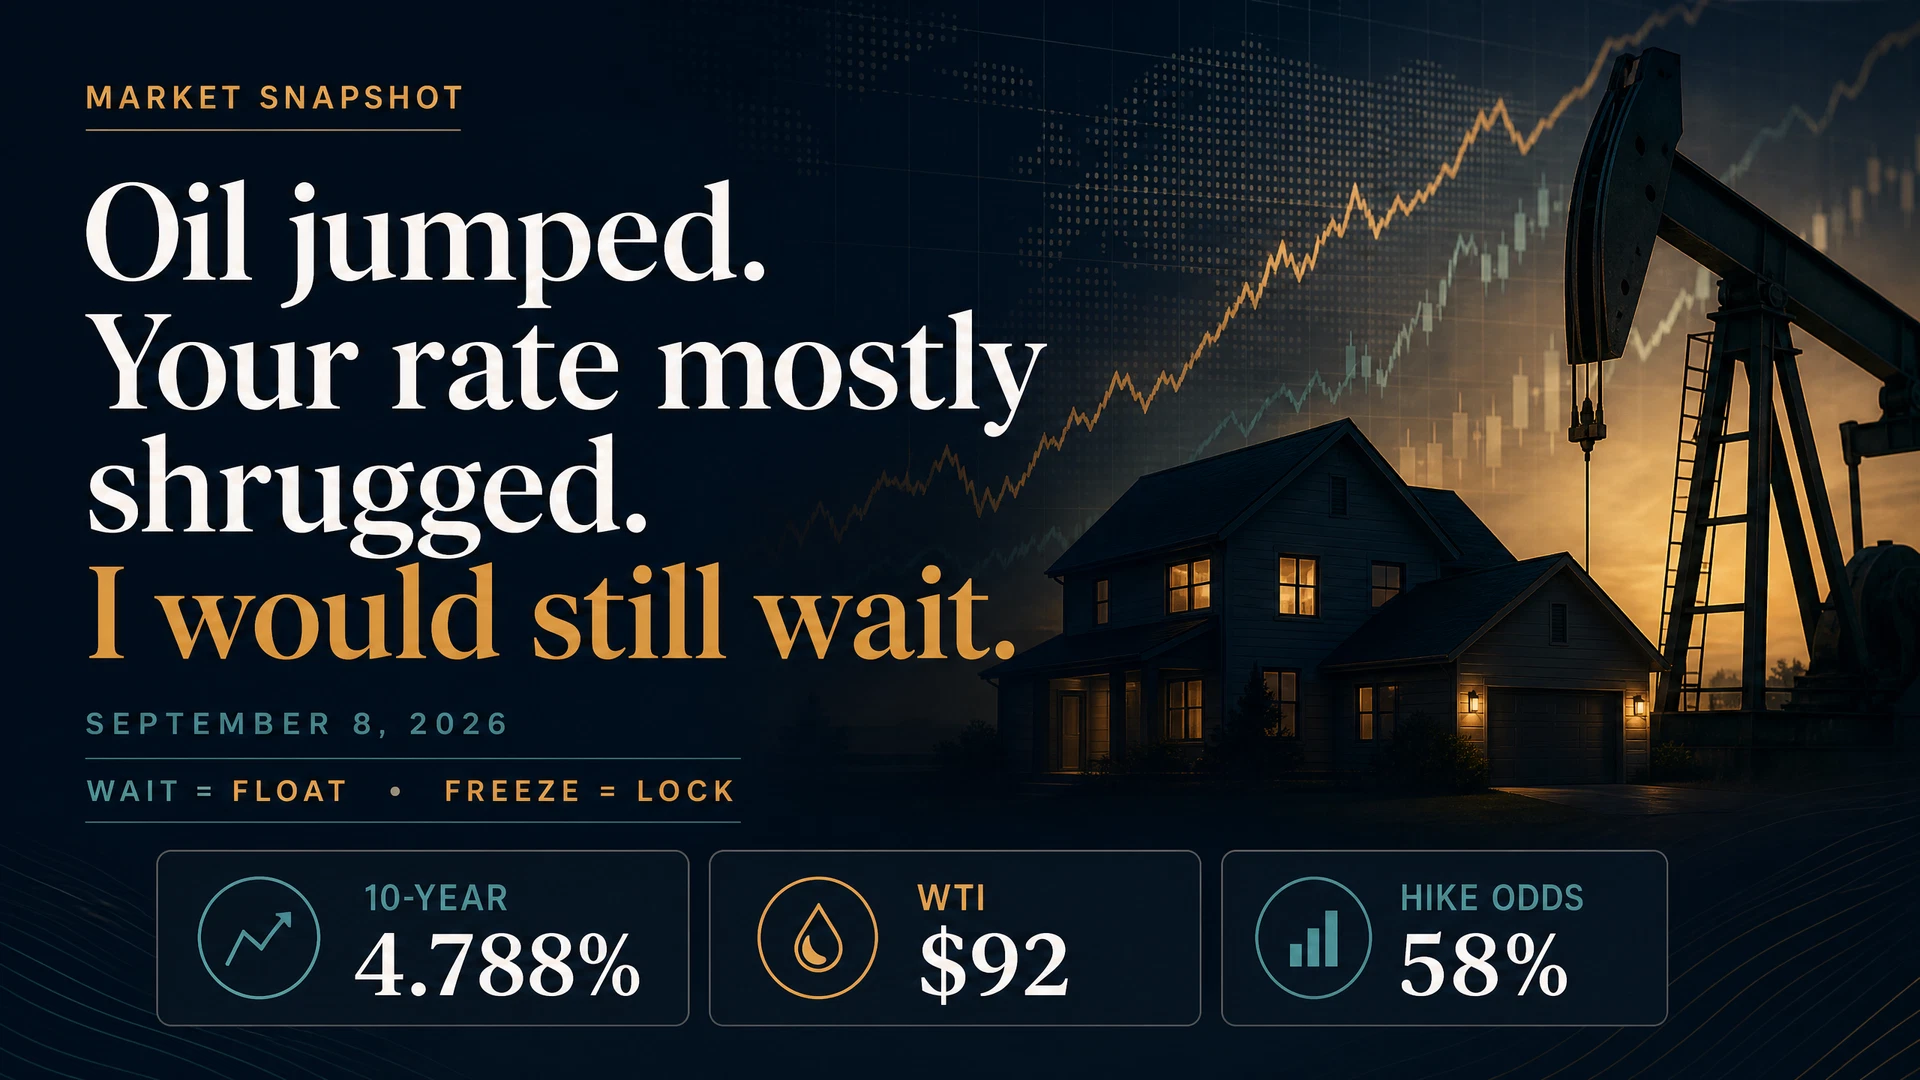
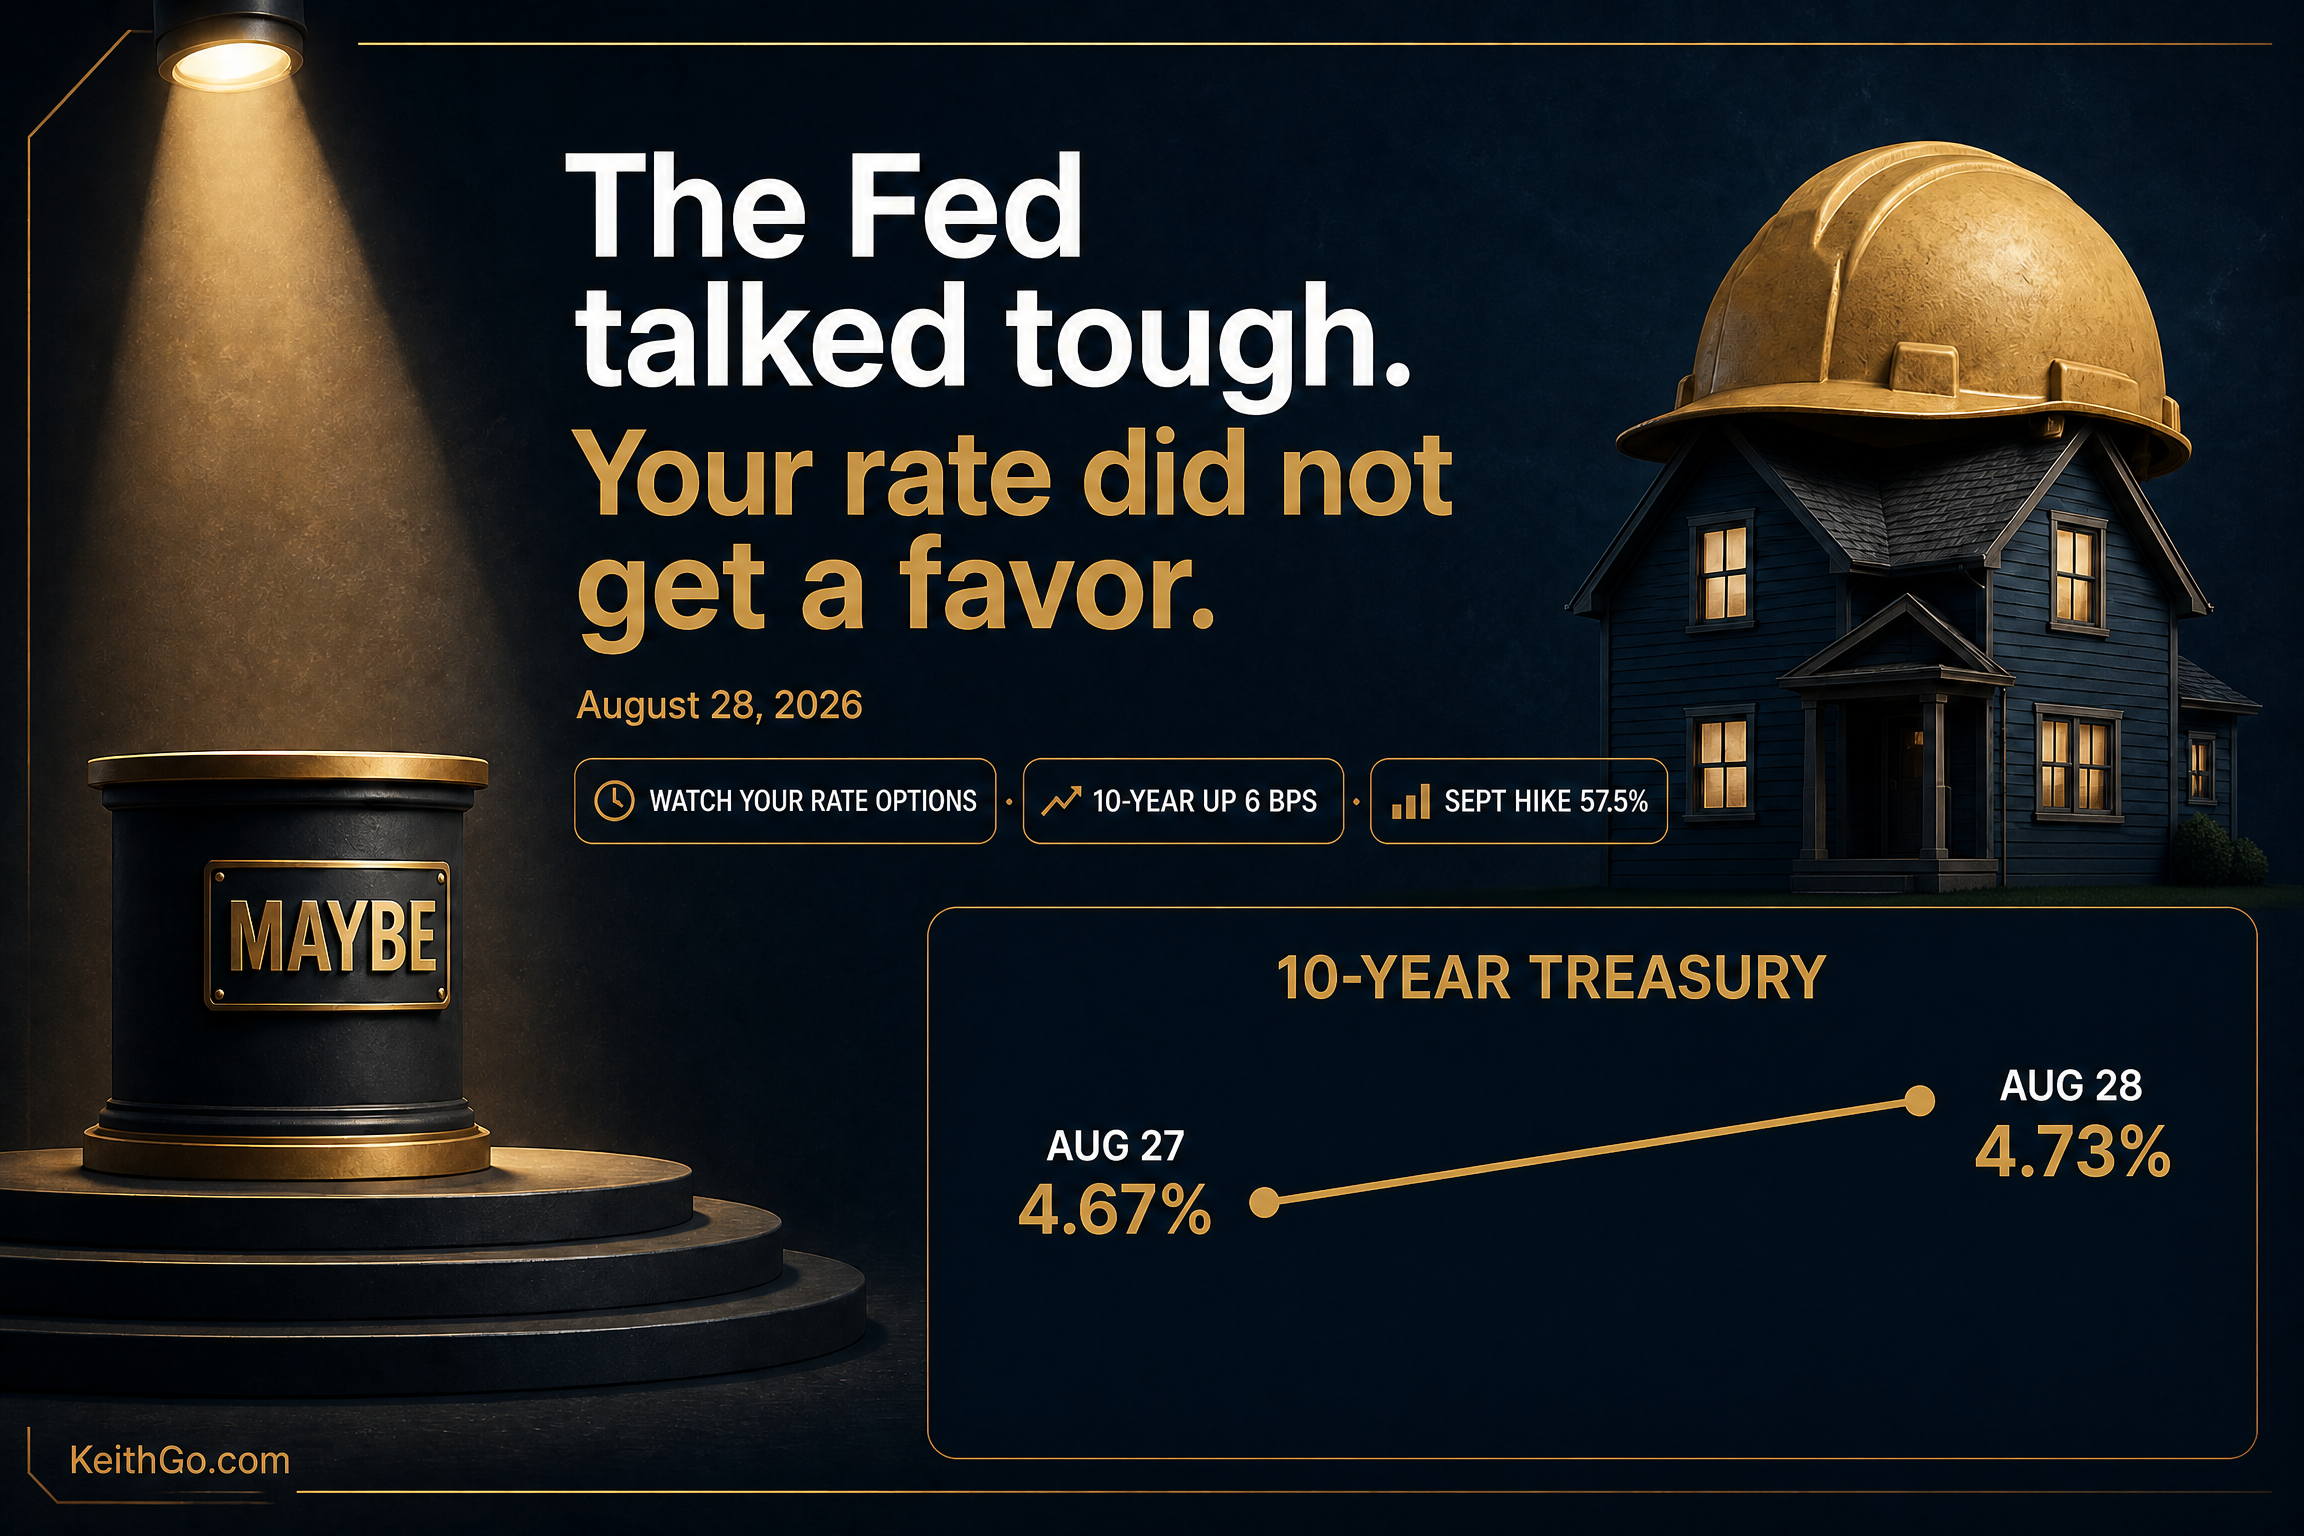
CNBC reported September hike odds at 57.5% late in the session, up from 35.4% one day earlier. Traders change their minds quickly, but that was a clear move after the speech.
What moved after the speech?
The official 10-year Treasury yield rose from 4.67% on August 27 to 4.73% on August 28. That is a 6-basis-point move.
The 10-year Treasury is not your mortgage rate. It is one of the quickest ways to see how the broader bond market is reacting.
The Federal Reserve does not set mortgage rates directly. Mortgage pricing also depends on mortgage-backed securities, lender capacity, servicing value, your loan details, and the market at the time you lock.
| Market measure | August 28 reading | What changed |
|---|---|---|
| 10-year Treasury | 4.73% | Up 6 basis points from August 27 |
| 2-year Treasury | 4.356% | CNBC reported a rise of more than 12 basis points |
| September hike odds | 57.5% | Up from 35.4% one day earlier |
The jobs report that needed a rewrite
Unemployment was 4.1%. That number needs context.
The Bureau of Labor Statistics released a preliminary benchmark revision for March 2026. The official revision was 79,000 fewer total nonfarm jobs. The preliminary private-sector revision was 178,000 fewer jobs.
Those figures are much smaller than the 879,000 number circulating in early market commentary. I am using the official BLS release here.
The civilian labor force also declined by 984,000 from May through July. A low unemployment rate can look stronger when fewer people are counted in the labor force.
Next week is jobs week
Three reports can move rate expectations.
- Tuesday, September 1: July Job Openings and Labor Turnover Survey.
- Wednesday, September 2: August ADP National Employment Report.
- Friday, September 4: August Employment Situation report.
A Reuters poll expected 45,000 jobs and unemployment at 4.2% for August. That is a forecast, not the result.
A stronger report could add to hike expectations. A weaker report could push the other way.
If you already have a rate sitting on a file
I am not treating this as a panic-lock day. Warsh did not hike. He also did not cut. He gave a speech and handed the next jobs report the keys.
I would start by asking whether floating still fits your file and keep a hand on the door. If the bond market sells off further, rates can move against you quickly.
If you are 30 to 45 days from closing, look at your lock period, points, lender credits, float-down rules, and how much payment change you can actually live with.
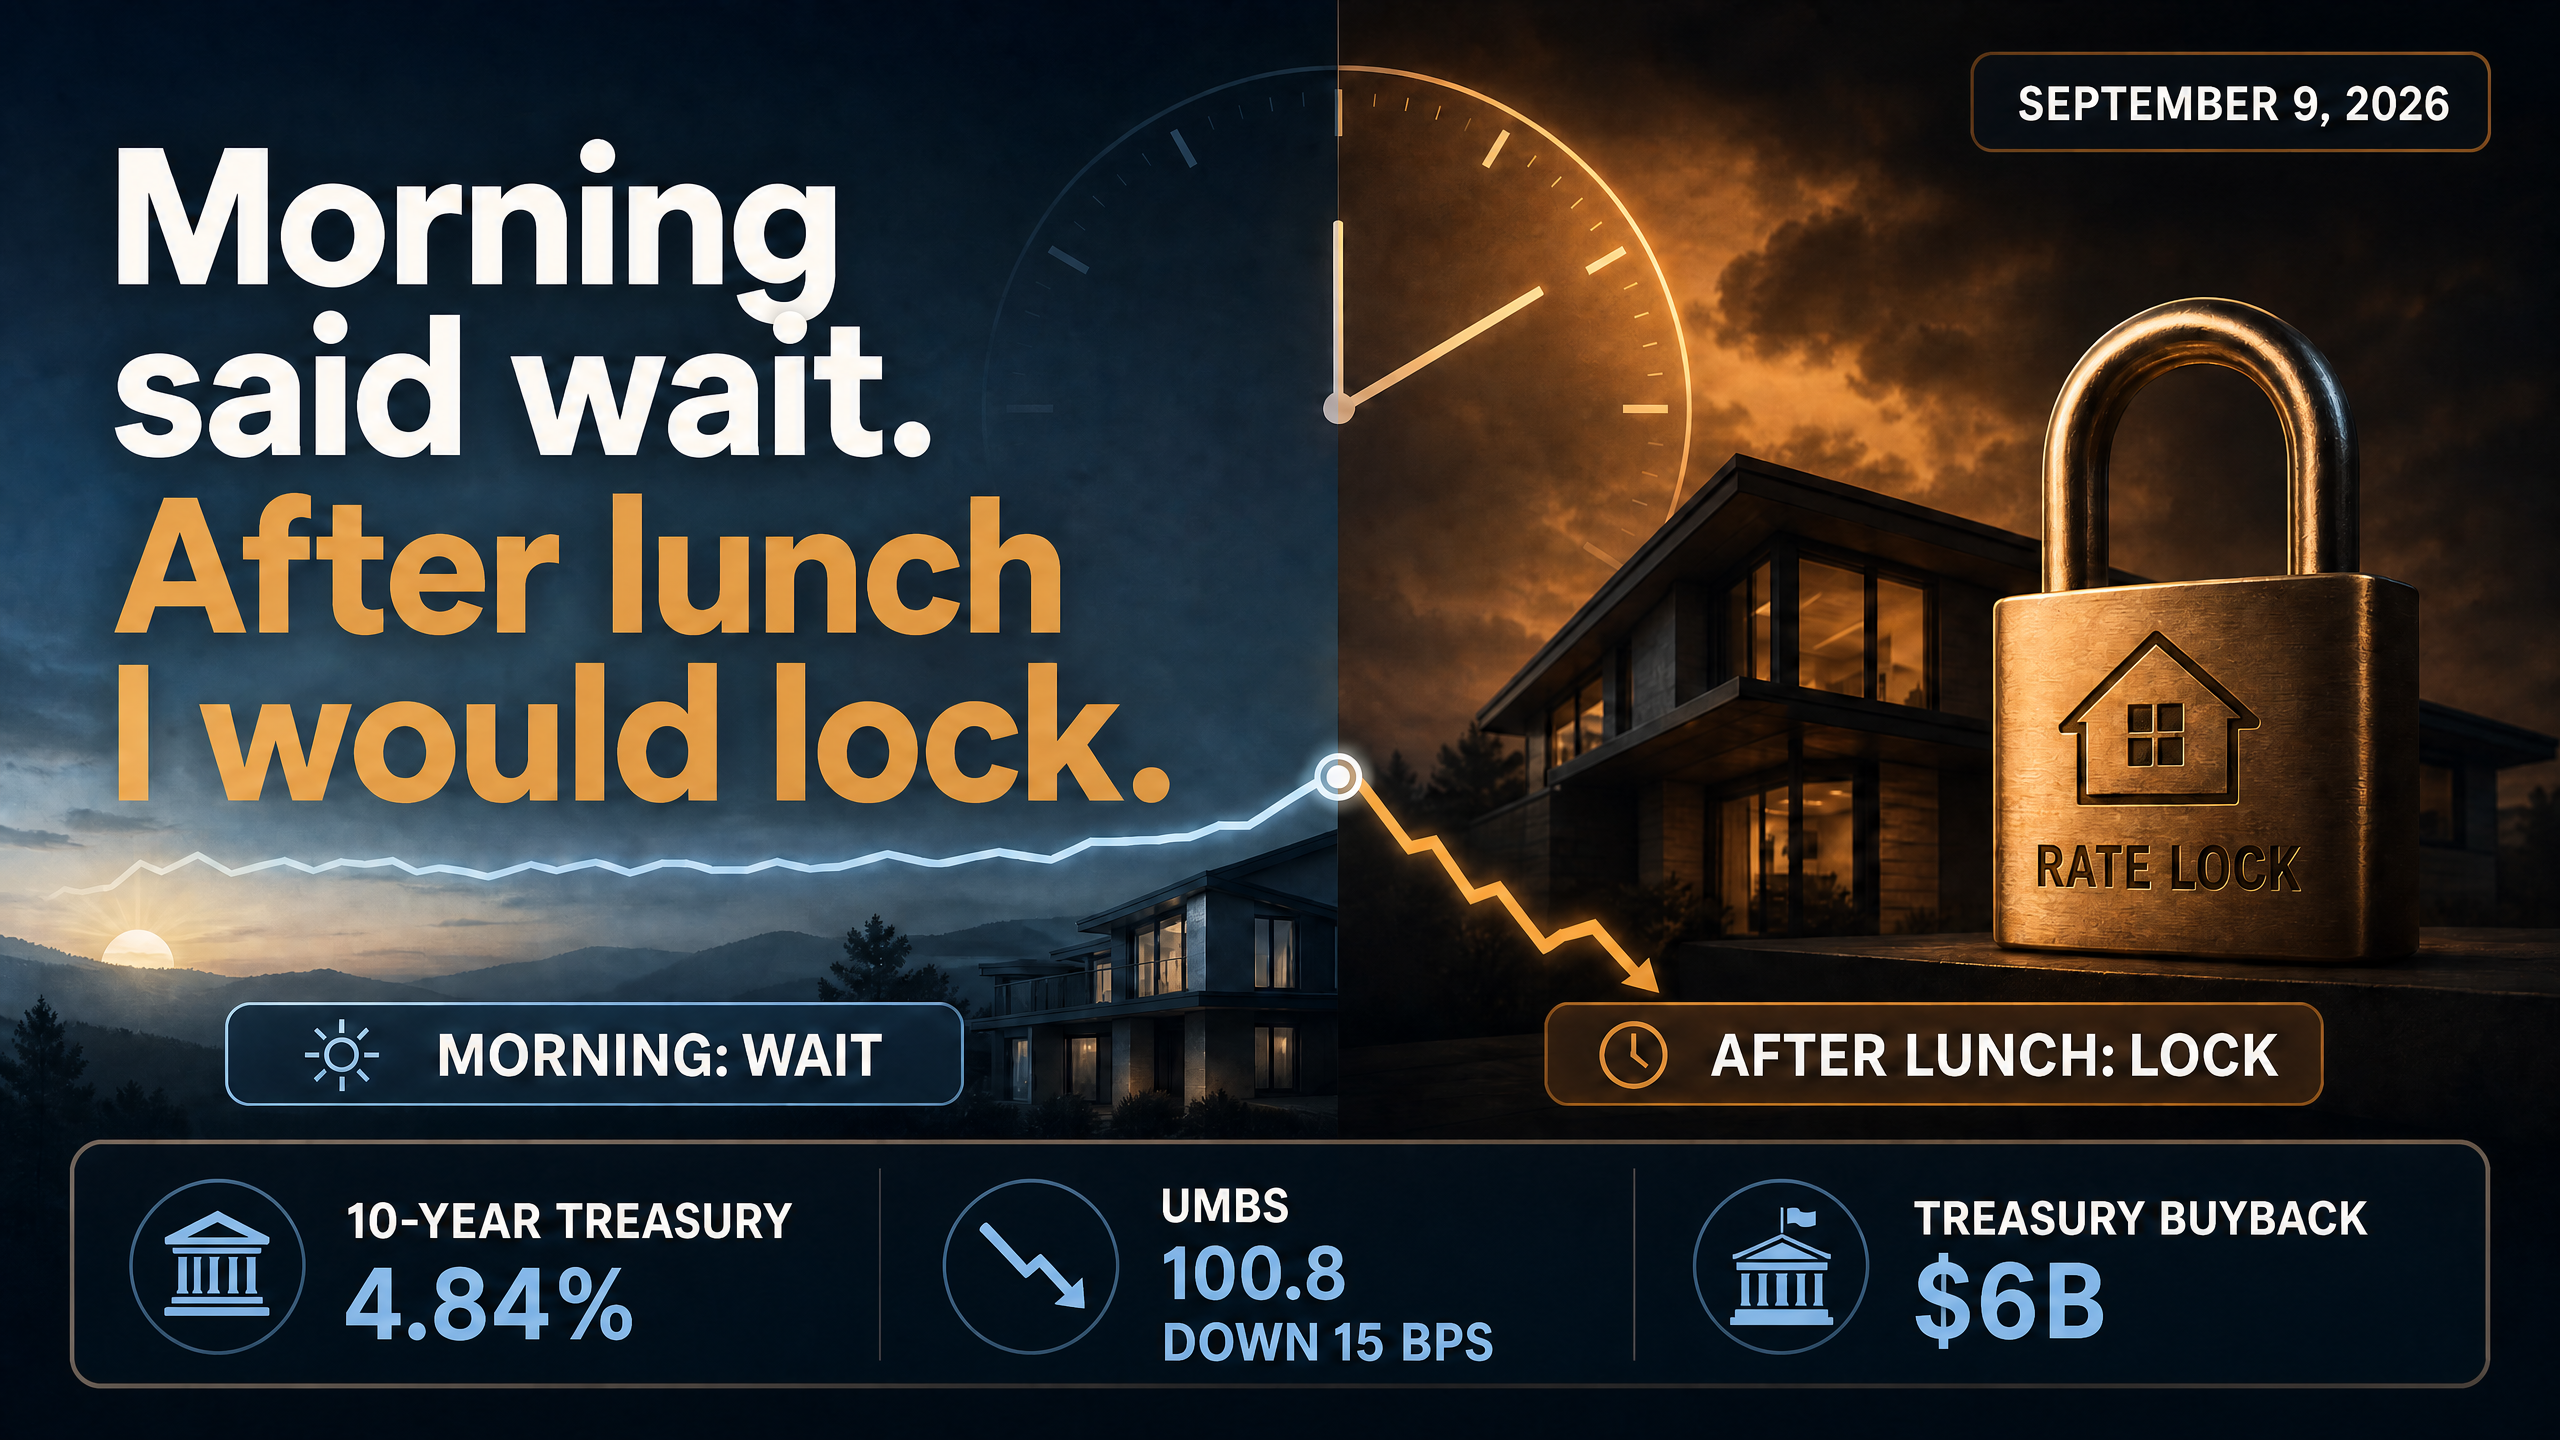
Waiting is a risk decision. So is locking. Make it from your numbers, not one headline.
If you are still shopping
Do not build your budget from yesterday’s quote and assume the speech did you a favor. It did not.
Run the payment at today’s price. Then run a higher-rate version so you know where the budget starts to hurt.
Follow the Ratewatch Daily section for the newest sourced market update.
What I would ask before deciding
- How many days are left before closing?
- What is today’s actual payment?
- How much worse can pricing get before the payment no longer works?
- Does the lender offer a float-down?
- What happens if the closing date moves?
- Are you paying points or receiving a lender credit?
Want me to run this against your numbers?
Send me the scenario or start the soft-check mortgage application. If you want to talk first, call or text me at 615-955-0461.
Sources and limitations
- Federal Reserve: Chairman Kevin Warsh’s August 28 Jackson Hole speech.
- CNBC: August 28 Treasury yields and CME FedWatch probability.
- U.S. Treasury: Daily par yield curve rates.
- Bureau of Labor Statistics: March 2026 preliminary benchmark revision.
- Bureau of Labor Statistics: July 2026 Employment Situation.
- Bureau of Labor Statistics: September 2026 release calendar.
- ADP: August report release schedule.
- Reuters: August jobs-report consensus.
Rates, Treasury yields, and futures probabilities can change during the day. This is dated market commentary, not an offer to lend, a personal rate quote, or a guarantee. Lock terms and float-down rules vary by lender and loan.