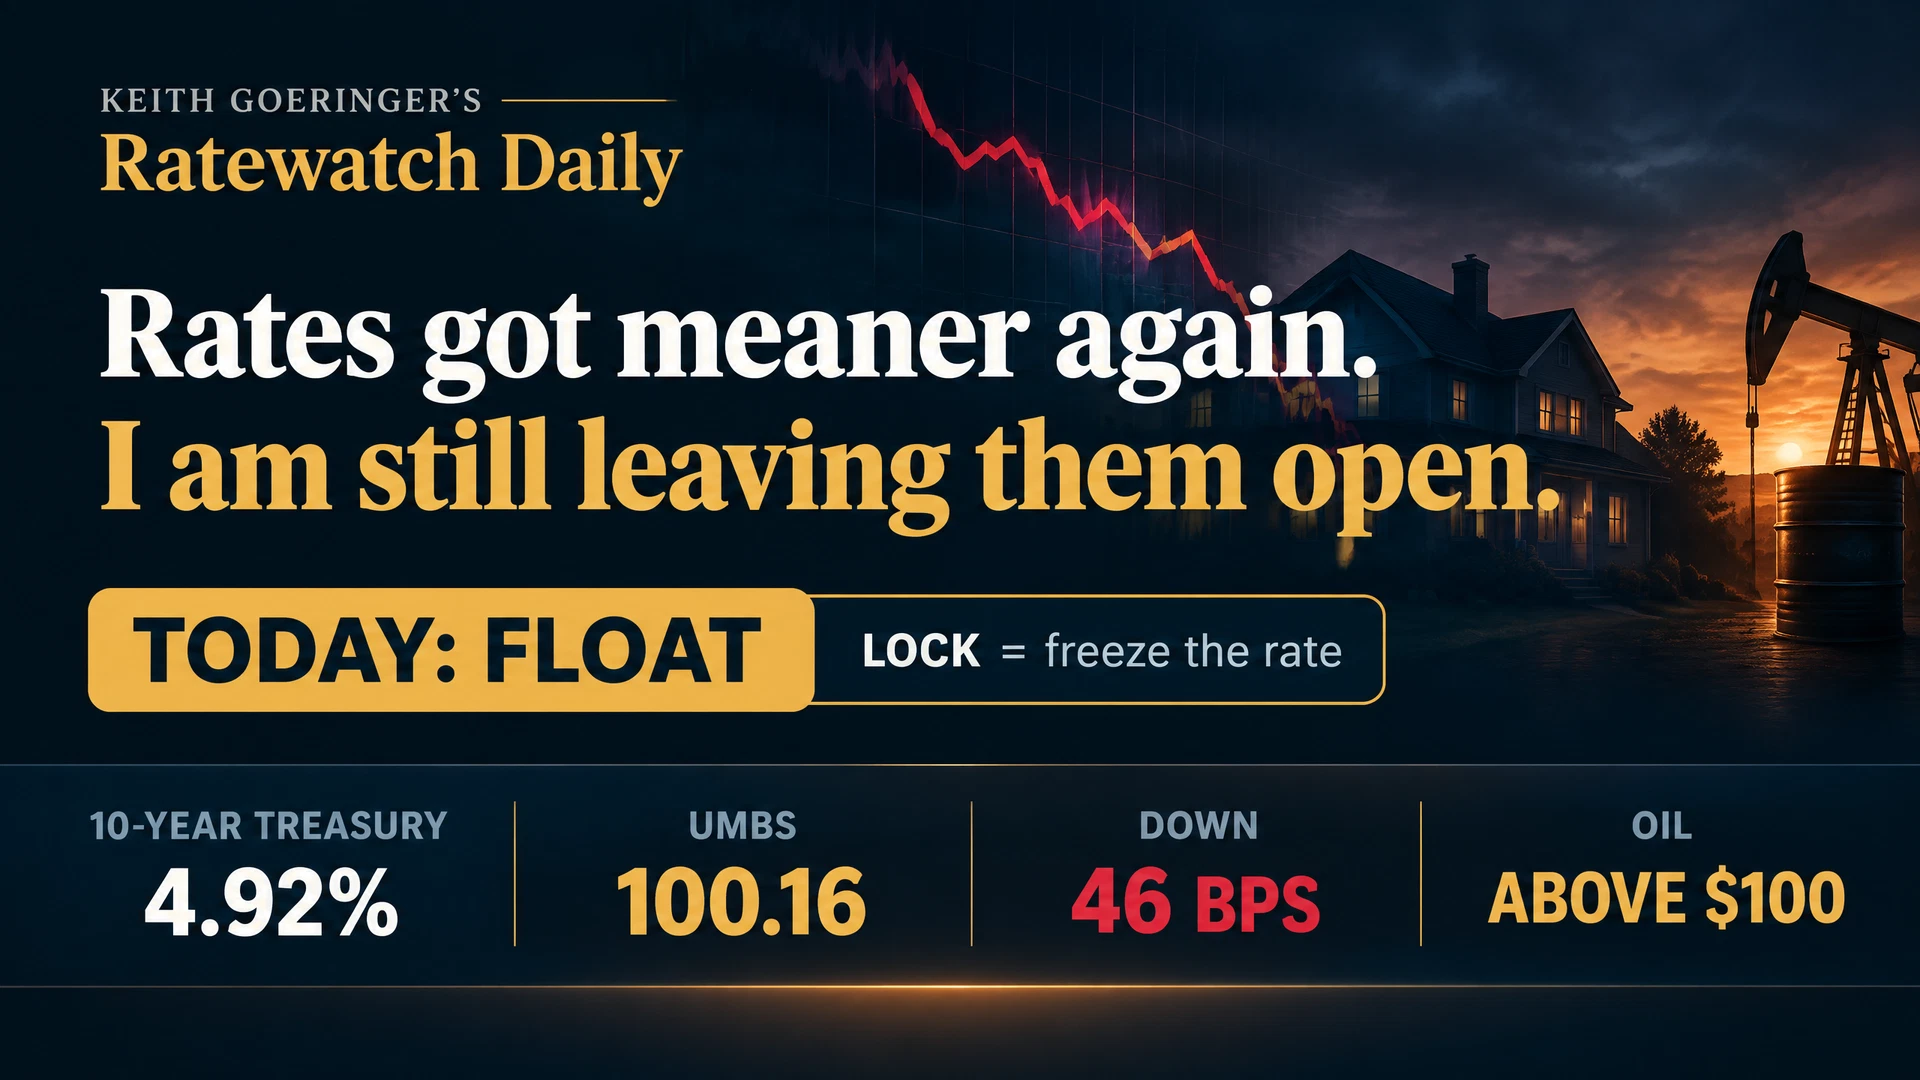
Oil jumped Tuesday. The 10-year Treasury did not follow it very far.
My call is to carefully float a loan already in process if the closing is not too close and the current payment has room to move.
That is a float. A lock freezes an agreed rate for a set period. Carefully floating means you wait, but you keep watching the market and the payment.
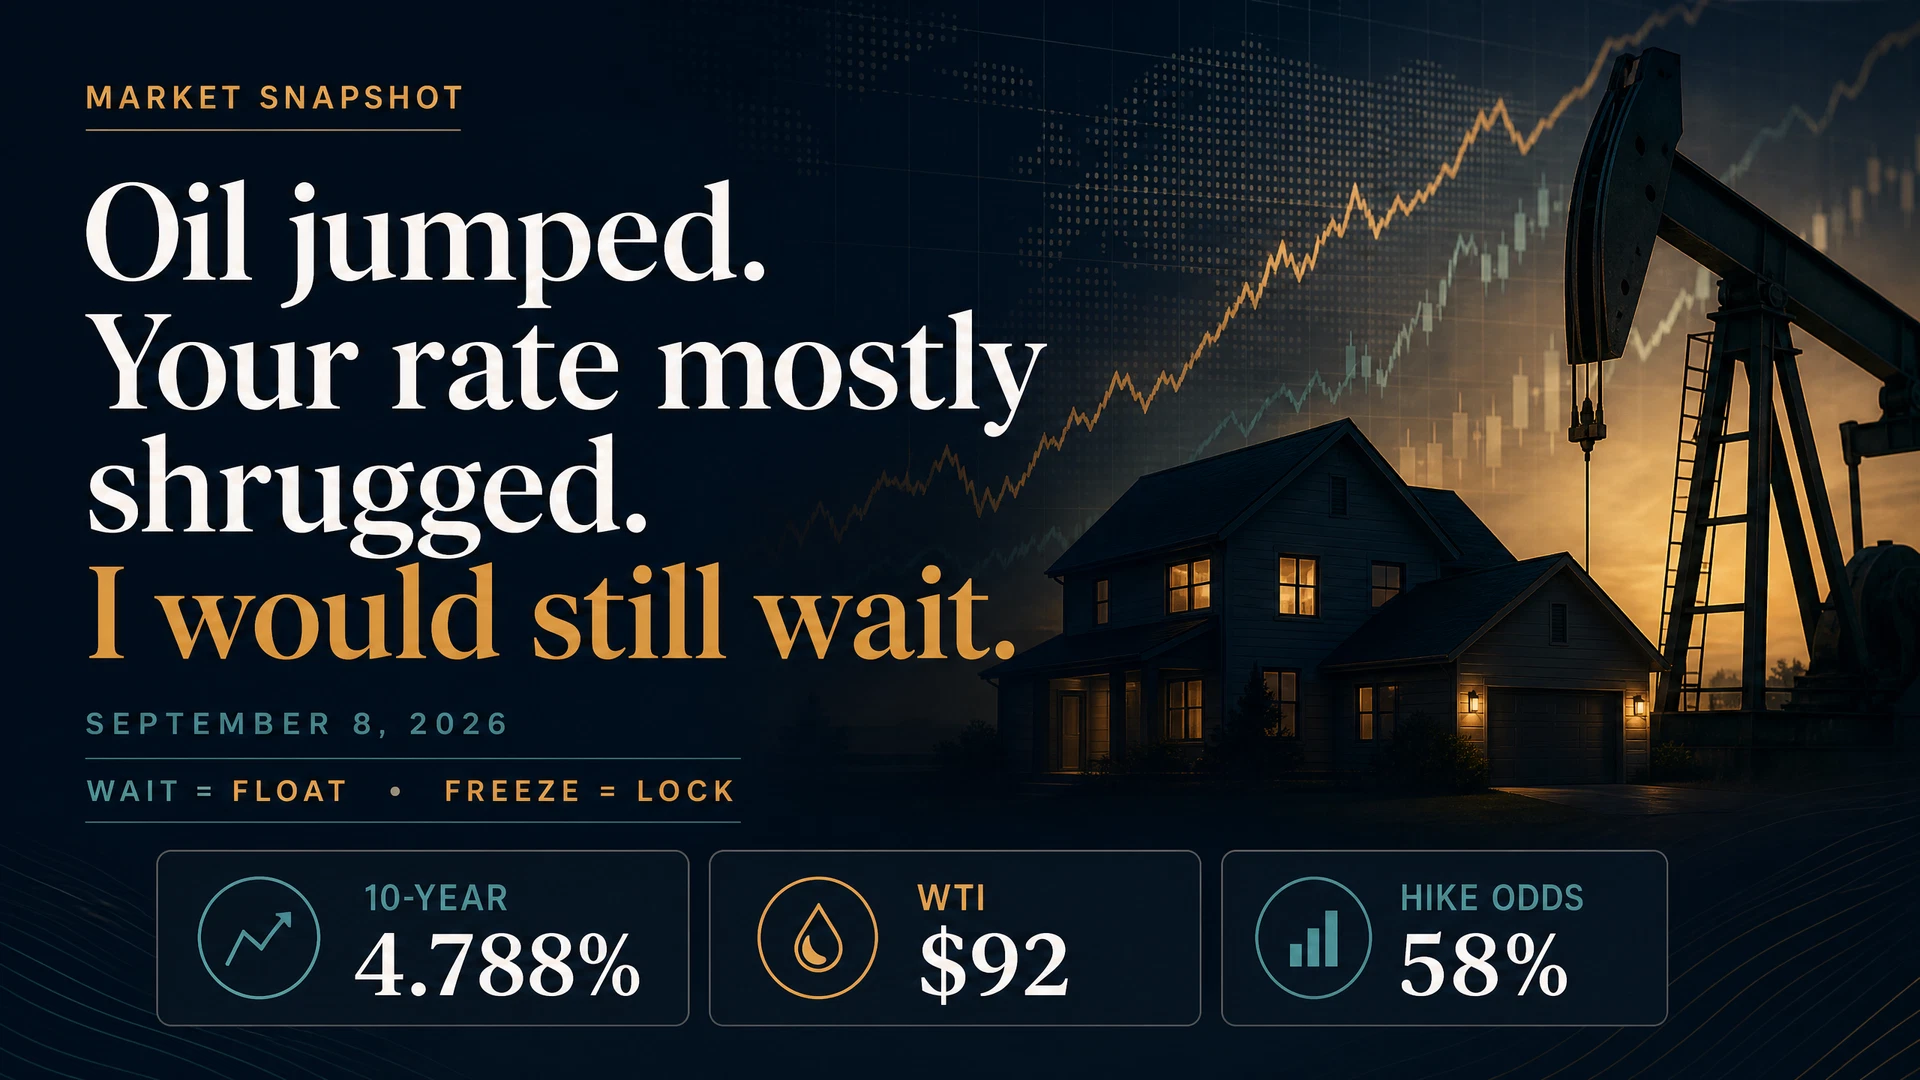
CNBC reported the 10-year Treasury yield at 4.788% and described it as little changed. West Texas Intermediate crude traded near $92 per barrel. Brent traded near $98.
Oil made the week louder. It did not settle the rate decision for every file.
How high did oil go?
Reuters reported Brent crude reached $99.46 during the day, its highest level since July 24.
The Associated Press reported Brent at $97.54 around midday after that high. CNBC put West Texas Intermediate near $92 and Brent near $98 in its market snapshot.
Those numbers describe two different oil benchmarks at different times. Do not turn them into one price.
Reuters also reported that U.S. diesel reached a record on September 3. That adds pressure to transportation costs, but it does not tell you what one mortgage rate should do next.
Why did the 10-year Treasury mostly shrug?
CNBC reported the 10-year Treasury yield at 4.788%, little changed for the session.
A later Associated Press report put it at 4.79%, up from 4.78%. That difference is timing.
A basis point is 0.01 percentage point. One hundred basis points equal one percentage point.
The 10-year Treasury is not your mortgage rate. Mortgage-backed securities, lender pricing, loan details, and market conditions still affect the rate offered on one file.
What is the market waiting for now?
The August Producer Price Index is scheduled for Thursday, September 10.
The August Consumer Price Index is scheduled for Friday, September 11. The Federal Reserve meets September 15 and 16, with its decision due September 16.
CNBC cited a FactSet forecast for headline CPI to rise 3.3% from a year earlier, down from 3.4% in July.
That is a forecast. Friday’s report can land above or below it.
Is a September Fed hike already decided?
No. CNBC reported a 58% market-implied chance of a quarter-point hike in its September 8 snapshot.
Reuters reported roughly 60% later in the day.
Those odds move with market prices. They are not a vote, a forecast from the Fed, or a promise about mortgage rates.
What does the mortgage-bond chart show?
The chart below is the mortgage-bond price snapshot supplied with this update.
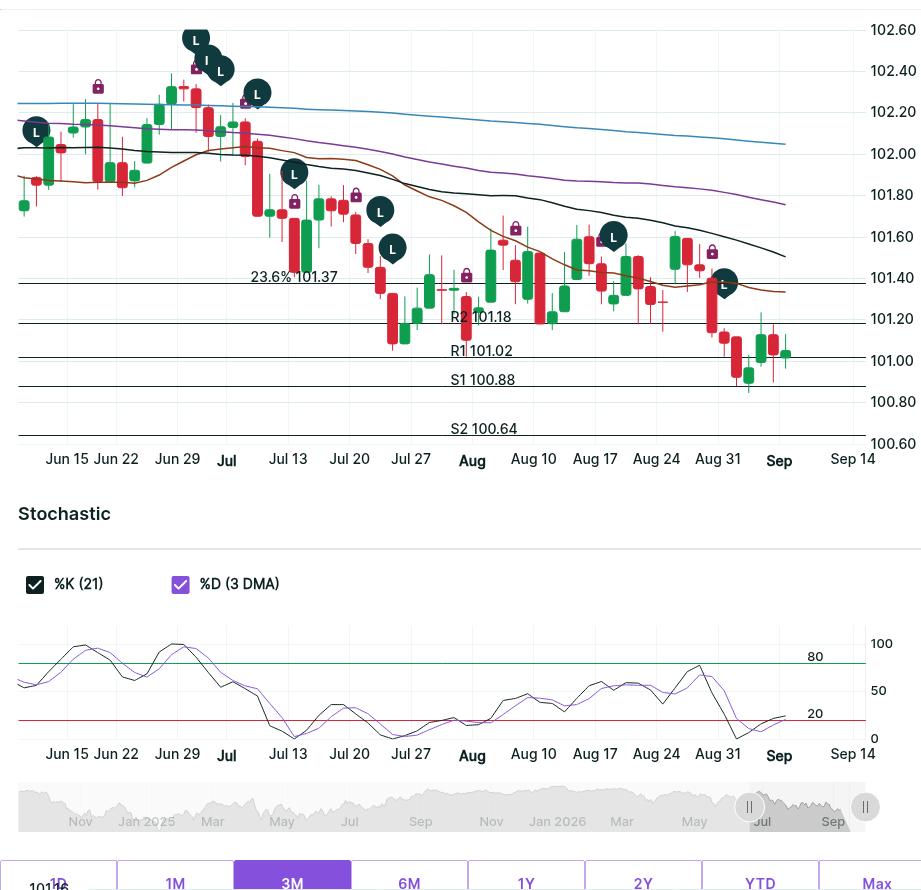
The chart labels 101.37, 101.18, 101.02, 100.88, and 100.64. Those are mortgage-bond price levels, not mortgage rates.
The image does not include a public timestamp, coupon identity, or independently verifiable data feed. I am using it as a market illustration. I am not using it to claim a floor will hold or to predict the next move.
What I would do today
I would carefully float if the closing is not too close and the current payment has room to move.
Then I would watch four things.
- How soon you close.
- How much payment movement you can tolerate.
- How long the available lock lasts.
- Whether a float-down is available if pricing improves later.
If the payment is already tight, your closing is close, or a quick market move would break the budget, waiting may not be worth it.
The Consumer Financial Protection Bureau’s rate-lock guide explains why lock periods, extension costs, and changes to the application matter.
If you are still shopping
Do not build your budget from last week’s quote. Run the payment again when you are ready to make an offer.
Use Why the Maximum Approval Is the Worst Number to Base Your Home Purchase On to separate what underwriting allows from what your household can live with.
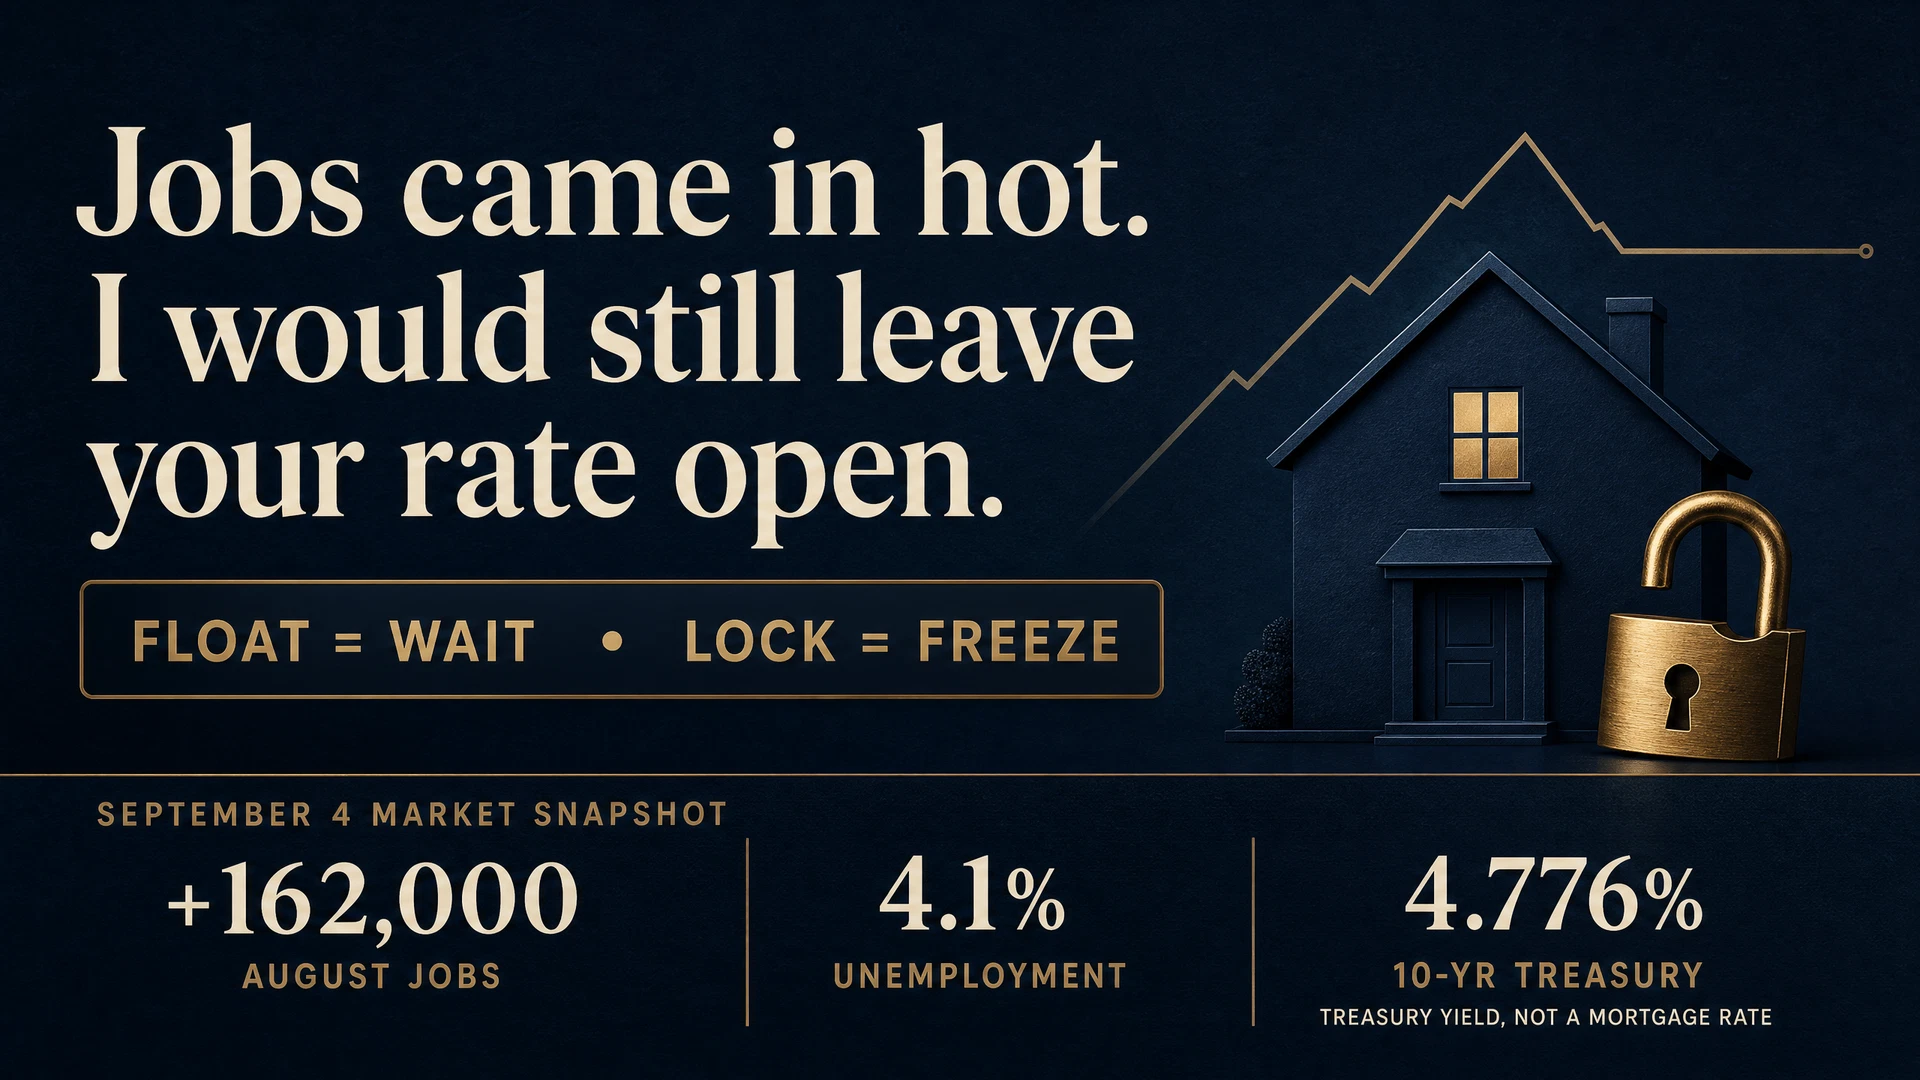
Friday’s setup is in Jobs Came In Hot. I Would Still Leave Your Rate Open.
Want me to check the file?
If you are 30 to 45 days from closing, send me the scenario through Ask Keith. I want to see the current payment, closing date, lock period, extension policy, float-down terms, and how much movement you can tolerate.
If you want to talk it through, book a mortgage call. If you are still looking, start the soft-check mortgage application before you make an offer.
Follow Ratewatch Daily for the next sourced market update.
Sources and limitations
- CNBC: September 8 Treasury yields, oil benchmarks, CPI consensus, and Fed probability.
- Reuters: September 8 Brent high, inflation calendar, and later Fed probability.
- Associated Press: September 8 Brent and 10-year Treasury market update.
- Reuters: U.S. diesel reached a record on September 3.
- Bureau of Labor Statistics: Producer Price Index release information.
- Bureau of Labor Statistics: Consumer Price Index release information.
- Federal Reserve: 2026 FOMC meeting calendar.
- Consumer Financial Protection Bureau: What is a rate lock?.
Treasury yields, oil prices, mortgage-bond prices, and futures probabilities change during the day. The figures above are September 8, 2026 snapshots from the cited times. The hero shows public Treasury, oil, and futures figures, not a mortgage-rate offer. The supplied chart is a user-provided market illustration, not an independently verified data feed. This article is dated market commentary. It is not an offer to lend or a promise that floating will produce a better outcome. Lock and float-down terms vary by lender and loan.