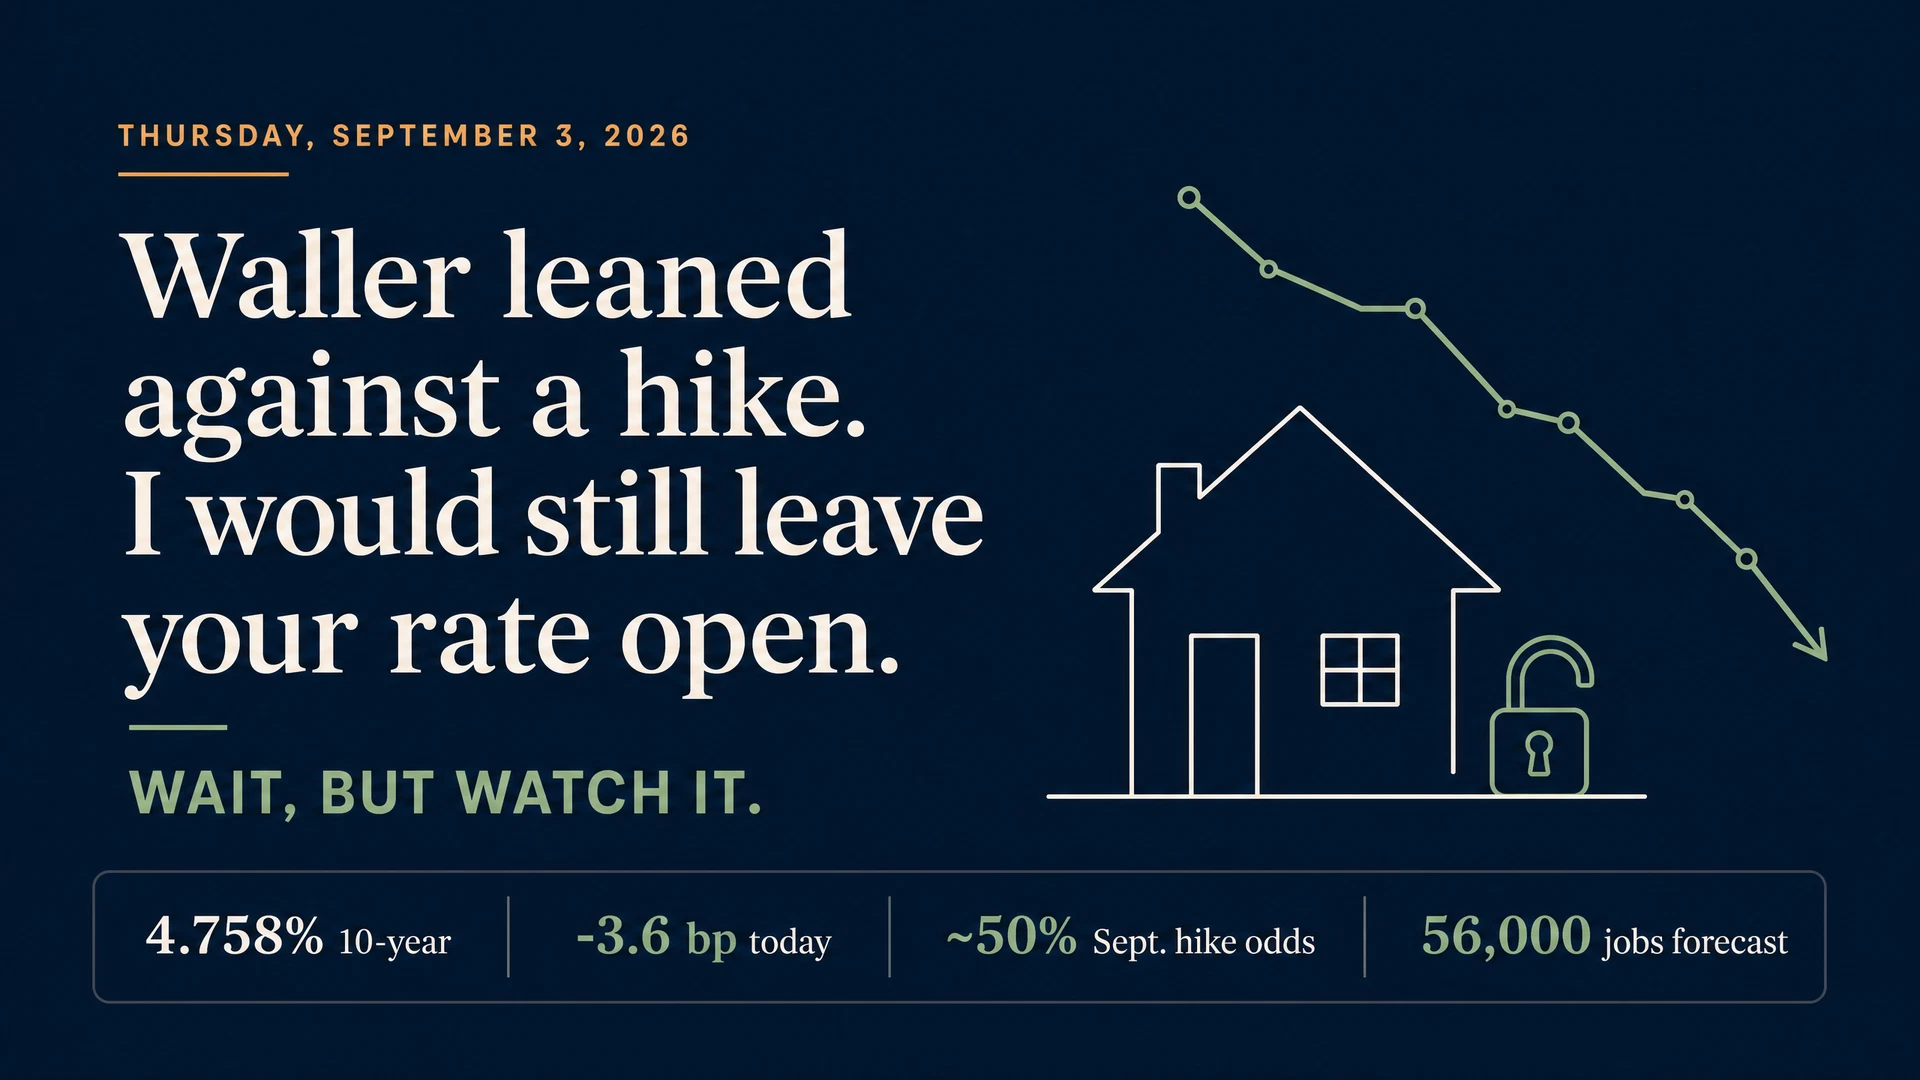
Waller’s comments gave the rate market some breathing room on September 3. I would still carefully float a loan already in process if the closing is not too close and the current payment has room to move.
Reuters reported the 10-year Treasury yield at 4.758%, down 3.6 basis points. Fed funds futures moved to roughly even odds of a September hike after Waller spoke.
That is relief. It is not a promise that rates improve again tomorrow.
My call is to wait, but watch it. Your closing date, lock period, float-down terms, and tolerance for a payment change still decide what fits your file.
What did Waller actually say?
Fed Governor Christopher Waller said he would support keeping rates unchanged at the September meeting if the August data showed continued progress toward the Fed’s 2% inflation goal.
He also left the door open to a hike if the inflation data came in hot.
That was enough to change the market’s view. Reuters reported that futures moved to roughly even odds of a September hike after Waller spoke. The prior session had priced a 63.2% chance of a hike.
The Fed meeting is September 15 and 16. The decision comes on September 16.
What happened to Treasury yields?
The 10-year Treasury yield moved down to 4.758% in Reuters’ afternoon market report. That was 3.6 basis points lower for the day.
A basis point is 0.01 percentage point. One hundred basis points equal one percentage point.
The yield had reached 4.818% on Wednesday, its highest level since November 1, 2023. Waller’s comments helped it back away from that high.
The 10-year is not your mortgage rate. Mortgage-backed securities, lender pricing, loan details, and market conditions still affect the rate offered on one file.
What did the labor data say?
Initial unemployment claims rose by 2,000 to 206,000 for the week ended August 29.
Continuing claims rose by 8,000 to 1.779 million for the week ended August 22.
That still looks like a slow-hire, slow-fire labor market. Layoffs remain limited, but finding the next job can take longer.
Wednesday’s ADP report showed 38,000 private jobs added in August. Education and health services added 45,000. Manufacturing lost 17,000. Leisure and hospitality added 16,000.
What is the market waiting for now?
The official August jobs report arrives Friday at 8:30 a.m. Eastern.
The latest Reuters survey expected 56,000 nonfarm payroll jobs and an unchanged 4.1% unemployment rate.
A weaker report could pull Treasury yields lower. A stronger report could revive the rate-hike case. Neither move is guaranteed.
Friday’s report is why I would not wander away from a floating file.
What did the mortgage-bond chart show?
The chart below is the intraday mortgage-bond snapshot supplied with this update.
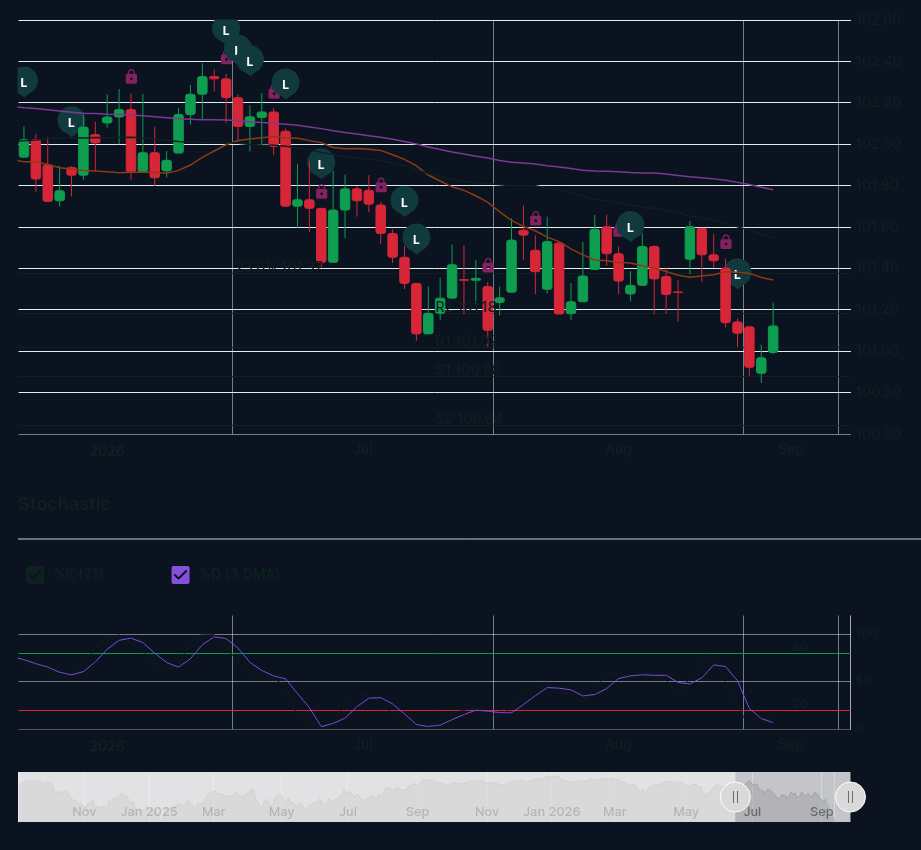
The visible chart labels include price levels near 101.02 and 101.18. Those are mortgage-bond prices, not mortgage rates.
The chart did not come with a public timestamp or an independently verifiable data feed. I am using it as an intraday illustration, not proof that one technical level must hold.
Did oil help?
Oil was still part of the inflation problem.
Reuters reported U.S. crude at $91.69 per barrel, up 0.74%, in its September 3 market update. Brent was $95.75.
Higher energy prices can add to inflation pressure. That is one reason the next inflation report still matters even after Waller leaned toward a hold.
What I would do today
I would carefully float if the closing is not too close and the payment has room to move.
Then I would watch four things.
- How soon you close.
- How much payment movement you can tolerate.
- How long the available lock lasts.
- Whether a float-down is available if pricing improves later.
If the payment is already tight, your closing is close, or a quick market move would break the budget, waiting may not be worth it.
The Consumer Financial Protection Bureau’s rate-lock guide explains why lock periods, extension costs, and changes to the application matter.
If you are still shopping
Do not budget from last week’s quote. Run the payment again when you are ready to make an offer.
Use Why the Maximum Approval Is the Worst Number to Base Your Home Purchase On to separate what underwriting allows from what your household can live with.
Yesterday’s setup is in ADP Was Anemic. I Would Still Leave Your Rate Open.
Want me to check the file?
If you are 30 to 45 days from closing, send me the scenario through Ask Keith. I want to see the current payment, closing date, lock period, extension policy, float-down terms, and how much movement you can tolerate.
If you want to talk it through, book a mortgage call. If you are still looking, start the soft-check mortgage application before you make an offer.
Follow Ratewatch Daily for the next sourced market update.
Sources and limitations
- Federal Reserve Board: Waller’s September 3 economic outlook and policy remarks.
- Reuters: Waller open to leaving rates unchanged if inflation cools.
- Reuters: September 3 Treasury yields, policy odds, and oil prices.
- Reuters: September 3 jobless claims and August payroll consensus.
- Reuters: August ADP private payroll report and sector details.
- Consumer Financial Protection Bureau: What is a rate lock?.
Treasury yields, oil prices, mortgage-bond prices, futures probabilities, and market forecasts change during the day. The figures above are September 3, 2026 snapshots from the cited times. The hero shows public market figures, not a mortgage-rate offer. The supplied chart is an intraday illustration, not an independently verified data feed. This article is dated market commentary, not an offer to lend or a promise that floating will produce a better outcome. Lock and float-down terms vary by lender and loan.